Bank statement analysis is the core of merchant cash advance underwriting. Because an MCA is repaid from daily or weekly deposits, the business bank statement tells a funder more about repayment ability than a credit score or a tax return does. This guide walks MCA brokers, ISOs, and funders through a seven-step method for reading statements, the math behind true revenue and burden, the red flags that should pause a deal, and how an MCA CRM keeps the analysis consistent from submission to renewal.
ConvergeHub works with MCA teams that want statement review, stipulations, and funding steps in one system instead of scattered spreadsheets and email threads. The method below works with any underwriting tool, and it gets faster when every file follows the same checklist inside a dedicated MCA CRM.
Bank statement analysis in MCA underwriting is the review of a merchant’s business bank transactions to measure true revenue, cash cushion, existing financing obligations, and document integrity before a funder purchases a share of future receivables. An MCA is structured as a purchase of future receivables rather than a loan, so there is usually no collateral or amortization schedule to fall back on. The cash flow in the account is the underwriter’s main protection.
That is why an MCA file looks different from a bank credit memo. Personal credit often works as a screening filter, while the statements decide the advance size, the holdback or fixed remittance, the factor rate, and the term.
Most MCA funders ask for three to six months of business bank statements for a first position, and many request a longer history for larger advances or seasonal businesses. A typical submission package includes:
Three months shows current performance. Six to twelve months shows seasonality, which matters for landscaping, construction, retail, and other businesses with strong peaks and slow periods.
The most reliable way to analyze bank statements for MCA underwriting is to run the same seven steps on every file:
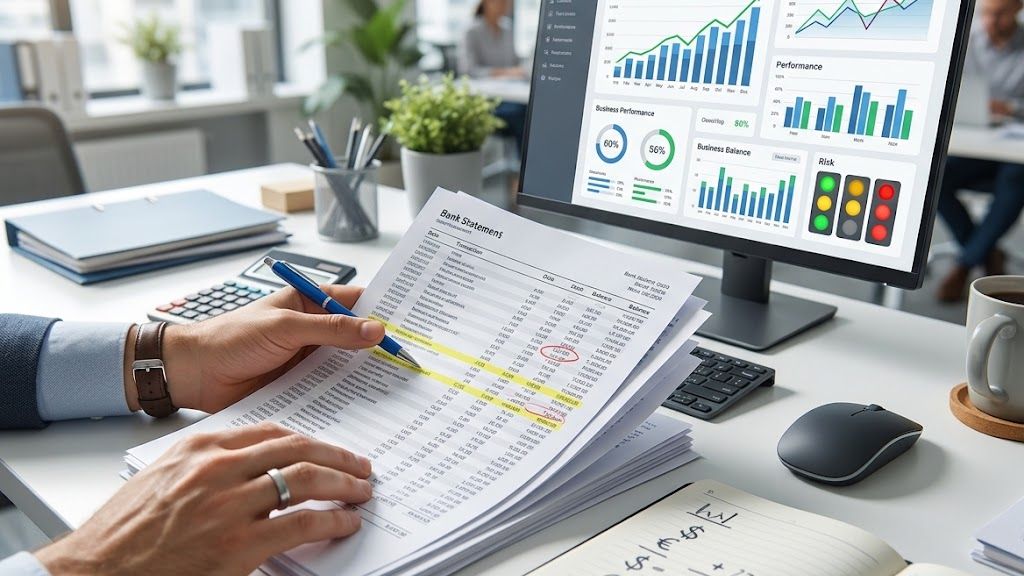
Start by checking that every month and every page is present, that the account holder name matches the application, and that the balances reconcile. Beginning balance plus credits minus debits should equal the ending balance, and each month’s ending balance should match the next month’s opening balance. A broken balance chain, missing pages, mismatched fonts, or a PDF that shows signs of editing is a reason to request a bank-verified copy or a direct bank connection before going further.
True revenue is the merchant’s real sales income after removing every credit the business did not earn from customers. It sets the maximum advance size, and gross deposits almost always overstate it.
| Credit type | Count as true revenue? | Reason |
|---|---|---|
| Card processor settlements | Yes | Sales income |
| Customer ACH payments, checks, and wires | Yes | Sales income |
| Transfers from the merchant’s other accounts | No | The same money moving between accounts |
| MCA or loan proceeds | No | Financing that carries its own repayment |
| Refunds, reversals, and chargeback credits | No | Reverses an earlier transaction |
| Owner capital injections | No | Owner funding, not business performance |
| Tax refunds and insurance payouts | No | One-time and non-recurring |
Record gross deposits and true revenue side by side for each month, with a note on what was excluded and why. That note lets a second reviewer or a funder check the work instead of redoing it.
Count deposit days per month and compare true revenue month over month. Daily remittance works best when deposits land on most business days, not in one or two large lumps. A merchant with steady true revenue is usually a stronger file than one whose higher average rests on a single strong month. Many underwriters also compare 30, 60, and 90 day averages and size the offer on the most conservative figure.
The average daily balance shows whether the account holds enough cash between deposits to absorb a daily or weekly debit. Track it alongside the lowest balance in each month, the number of negative-balance days, and the count of NSF or returned items.
NSFs and negative days measure different things. An NSF means a payment bounced or was returned, while a negative day means the account dipped below zero and recovered, often through overdraft coverage. Most MCA remittances move over the ACH Network, whose operating rules are developed and administered by Nacha, so a failed funder debit usually appears on the statement as a returned ACH item with a fee. A pattern of returned debits to a funder signals that the merchant is already struggling to carry an existing position.
An existing position is an active advance the merchant is still repaying. Positions appear as equal debits on a fixed daily or weekly rhythm, usually to a lender-like payee. Group every debit by payee across the full statement period, then apply a cadence check: fixed daily or weekly debits usually indicate an MCA, while monthly debits usually indicate a term loan or equipment note.
MCA stacking is when a merchant takes a new advance while earlier ones are still being repaid. Watch for a large funding credit followed by a new recurring debit, since that shows a position opened during the statement window. A new payee with only one or two debits should be flagged for review rather than counted, because its rhythm is not established yet.
MCA burden is the share of true revenue already committed to financing payments. Add all position payments for the month and divide by true revenue, not gross deposits. Here is an illustrative example:
Every funder sets its own threshold, but burden that climbs toward half of true revenue generally signals serious repayment pressure. The figure you report should always state which denominator you used.
Finish with a short, sourced summary instead of a transaction dump. A useful underwriting summary covers monthly true revenue with exclusions, deposit days, average daily balance, NSF and negative-day counts, existing positions with daily payment amounts, burden before and after the proposed advance, document-integrity findings, and open questions for the merchant. Many funders then map the file to an internal paper grade, commonly A through D, that drives advance size, factor rate, and term.
Some findings should pause a deal until the merchant or broker explains them:
None of these proves fraud on its own. Each one is a reason to request verification and record the answer on the file.
Manual review with a spreadsheet can be accurate, but it is slow and depends heavily on the individual underwriter. Automated bank statement analysis tools parse transactions, group debits, and run the math in minutes, which frees the underwriter to focus on judgment calls.
| Factor | Manual review | Automated analysis |
|---|---|---|
| Speed | Line-by-line entry on every file | Transactions parsed in minutes |
| Consistency | Varies by reviewer and workload | Same rules applied to every file |
| Stacking detection | Easy to miss a small daily debit | Debits grouped by payee and cadence |
| Audit trail | Notes in a spreadsheet | Figures linked to source transactions |
| Final decision | Underwriter | Still the underwriter |
The practical model is software for extraction and math, and people for the decision.
Analysis tools read the statement. An MCA CRM manages everything around it: who requested the statements, what is still missing, where the summary lives, and what happens next. If you are still weighing what a merchant cash advance CRM does, this is the part of the process where the difference shows most clearly.
ConvergeHub creates a document checklist for each deal and sends automated reminders when bank statements, processing statements, or month-to-date stips are missing, so files reach underwriting complete.
Each deal in ConvergeHub is a trackable case with an assigned owner, milestones, and a full communication timeline. Storing true revenue, burden, position count, and red-flag notes on that record [CLIENT TO CONFIRM: custom fields for underwriting metrics] means the next reviewer sees the same numbers and the reasoning behind them. Shared visibility like this is central to the features MCA teams actually need from a CRM.
Milestone alerts show when a file moves from submission to underwriting, offer letter, stips, and funding. Offer letters can be sent, signed, and tracked inside the CRM with a complete audit trail, so nobody chases status updates by email.
ConvergeHub tracks renewal opportunities against the original deal record. When a merchant returns, the earlier statement summary gives the underwriter a baseline for comparing revenue trend, balance behavior, and positions, which matters for any team focused on growing an MCA business through repeat funding.
Most MCA underwriters review three to six months of business bank statements, and many ask for a month-to-date statement before funding. Larger advances and seasonal businesses often require six to twelve months so the underwriter can see slow periods as well as peaks.
True revenue is the merchant’s actual sales income after removing transfers between the merchant’s own accounts, loan or MCA proceeds, refunds, reversals, owner injections, and one-time credits. It is the correct base for sizing an advance and calculating burden.
There is no single industry standard, and each funder sets its own limit. Lower burden means more room for a new position, and burden approaching half of true revenue generally signals significant repayment pressure. Always calculate it on true revenue rather than gross deposits.
Underwriters group every debit by payee and look for fixed daily or weekly payments to lender-like counterparties. They also watch for large funding credits followed by new recurring debits, which show a position opened during the statement period.
Many run a soft credit check as a screening step, but credit carries less weight than cash flow. Because repayment comes from daily or weekly deposits, the bank statements usually decide the file.
Careful bank statement analysis wins more deals when every file follows the same steps and every result lands in one place. See how ConvergeHub organizes statements, stips, offer letters, and renewals for MCA teams when you request a ConvergeHub demo.