Merchant cash advance disclosure requirements now apply in eleven states, and a twelfth law is scheduled to take effect in 2027. Each state sets its own dollar thresholds, disclosure fields, and registration rules, so a broker or funder working across state lines needs a reliable way to know which rules apply to each deal. This guide covers which states have MCA disclosure laws, what a compliant disclosure typically includes, and how to track every requirement inside your CRM.
ConvergeHub helps MCA brokers and funders keep deal steps, documents, and offer letters in one system. Compliance works best when it is built into that same workflow, which is why a dedicated merchant cash advance CRM is a practical place to manage state disclosure rules.
This article is general information, not legal advice. State laws and regulations change, so confirm current requirements with qualified counsel or the relevant state regulator before relying on them.
Merchant cash advance disclosure requirements are state laws that require providers, and in some states brokers, to give a business a standardized written summary of the cost and terms of a financing offer before the deal is signed. Because an MCA is structured as a purchase of future receivables rather than a loan, it has historically fallen outside federal Truth in Lending Act disclosures. State commercial financing disclosure laws fill that gap for sales-based financing and, in many states, for other commercial products such as factoring and small business loans.
These laws regulate transparency, not price. Most do not cap factor rates or fees. They focus on making sure a merchant can see the real cost of an offer and compare it with other options.
As of September 2026, eleven states have enacted commercial financing or sales-based financing disclosure laws that can cover merchant cash advances. Coverage depends on the merchant’s location, the financing amount, the product type, and whether the provider qualifies for an exemption.
| State | Coverage limit | Estimated APR required? | Registration | In effect |
|---|---|---|---|---|
| California | $500,000 or less | Yes | No; annual report to DFPI by March 15 | Dec 9, 2022 (SB 362 updates Jan 1, 2026) |
| New York | $2.5 million or less | Yes | None under the CFDL | Aug 1, 2023 |
| Utah | $1 million or less | No | Providers register | Jan 1, 2023 |
| Virginia | $500,000 or less (sales-based) | No | Providers and brokers register | 2022 |
| Florida | $500,000 or less | No | No | Jan 1, 2024 |
| Georgia | $500,000 or less | No | No | Jan 1, 2024 |
| Connecticut | $250,000 or less (sales-based) | No | Providers register annually | Jul 1, 2024 |
| Kansas | $500,000 or less | No | No | Jul 1, 2024 |
| Missouri | $500,000 or less | No | Brokers register | 2025 |
| Texas | Under $1 million (sales-based) | No | Providers and brokers by Dec 31, 2026 | Sep 1, 2025 |
| Louisiana | No dollar cap (revenue-based) | No | No | Aug 1, 2025 |
Two more developments are worth tracking. Vermont enacted Act 142 in June 2026, which brings sales-based financing and factoring under a licensing and disclosure framework starting July 1, 2027. New Jersey has disclosure bills pending but, as of this writing, no enacted law. Teams that offer factoring or revenue-based financing alongside MCAs should note that several of these laws reach those products too, which is where an alternative lending CRM with configurable deal types helps.
Formats differ by state, but most MCA disclosures must show the merchant some combination of the following before the deal closes:
Estimated APR is usually the hardest field for MCA providers, because an advance has no fixed term. States that require it prescribe how to estimate the term and payment schedule, so the calculation method should be documented and applied the same way on every offer.
Most compliance gaps are process gaps, not knowledge gaps. The common failure points are:
Each of these is a tracking problem. Spreadsheets and inboxes rarely show, at a glance, which state rules apply to a deal and whether every required step has been completed.
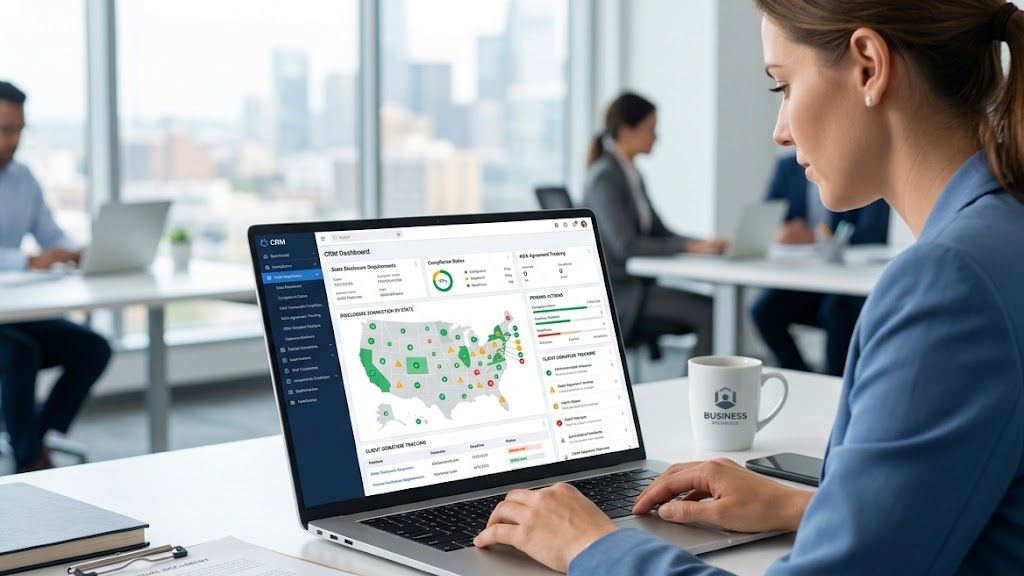
A CRM does not replace legal review or a compliant disclosure template. It makes sure the right template goes out on the right deal at the right time, and that you can prove it later. These seven steps turn disclosure rules into a repeatable workflow.
Record the state where the merchant’s business is principally directed or managed on the deal record at the first touch. That single field decides which disclosure law, if any, applies, so make it required from the start. In ConvergeHub, an admin can add this as a custom list field on the Deals module and set it as mandatory, so a deal record cannot be created or updated without it.
Store whether the offer is a merchant cash advance, revenue-based financing, factoring, or a loan, along with the offer amount. Several laws apply only to sales-based financing, and every state except Louisiana has a dollar cap, so these two fields let your team test coverage in seconds.
Keep one internal reference, reviewed by counsel, that lists each state’s threshold, required fields, APR rule, and registration status. Link it from the deal workflow so reps and underwriters check the same source instead of relying on memory. Update it whenever a state changes its rules, and note the review date.
ConvergeHub lets teams send, sign, and track offer letters inside the CRM with a complete audit trail. Add the state disclosure to that same milestone so an offer cannot move to funding until the disclosure is delivered and acknowledged. When the disclosure and offer share one step, the file never has one without the other. These are the kinds of workflow features MCA teams actually need from a CRM.
Store the signed disclosure on the deal record with the template version, the date it was sent, and the date it was signed. ConvergeHub’s merchant communication timeline keeps every interaction on one record, so a reviewer can see exactly what the merchant received. Retain these records for the period your counsel recommends.
ConvergeHub tracks renewal opportunities against the original deal record. Build a rule that treats every renewal or refinance as a new offer requiring a fresh disclosure, including the amount used to pay off the existing balance where the state requires it. Texas, for example, requires that payoff information on renewal financing.
Registration and reporting dates are easy to miss because they happen once a year. Create recurring tasks with owners for each obligation, such as California’s March 15 annual report, Connecticut’s annual registration, and Texas’s December 31, 2026 registration deadline. Texas registration runs through NMLS, the licensing platform that the Conference of State Bank Supervisors owns and operates on behalf of state regulators. Automated reminders keep these dates visible to the whole team instead of one person’s calendar.
Texas also limits automatic debits unless the provider holds a first-priority perfected security interest. Because most MCA remittances run as ACH debits governed by operating rules that Nacha develops and administers, collection setup is worth reviewing alongside the disclosure workflow.
Disclosure files contain financing terms, bank details, and owner information, so they deserve the same protection as any sensitive customer data. Limit access by role, require strong authentication, and keep records in one secure system instead of shared drives and email attachments. Review your CRM security practices for storing customer data before moving compliance records into any platform.
California and New York require an estimated APR in their commercial financing disclosures. Most other disclosure states require cost, repayment, and payment terms without an APR. Vermont’s Act 142, effective July 1, 2027, will also require an estimated APR on every specific offer.
In some states, yes. Virginia, Connecticut, and Texas require both providers and brokers to register, Missouri requires broker registration only, and Utah requires provider registration. Starting July 1, 2027, Vermont will require providers and brokers to be licensed. Requirements depend on your role in the transaction.
Providers and brokers of commercial sales-based financing in Texas must register with the Office of Consumer Credit Commissioner by December 31, 2026, and renew annually. The law’s disclosure requirements took effect September 1, 2025.
In most disclosure states, a renewal or refinance is a new financing offer that requires a new disclosure. Some states also require showing how much of the new funding pays off the prior balance.
An MCA is generally structured as a purchase of future receivables rather than a loan, which is why it falls outside many lending laws. State disclosure laws still apply to MCAs when the transaction meets their coverage rules.
A CRM cannot replace legal advice or a compliant disclosure template. It helps by capturing the right data at intake, attaching the correct disclosure to each offer, recording signatures, and tracking renewals and registration deadlines.
State disclosure rules are multiplying, and the teams that keep up are the ones that build them into daily deal flow. See how ConvergeHub keeps offer letters, documents, renewals, and deadlines on one record when you book a ConvergeHub demo.