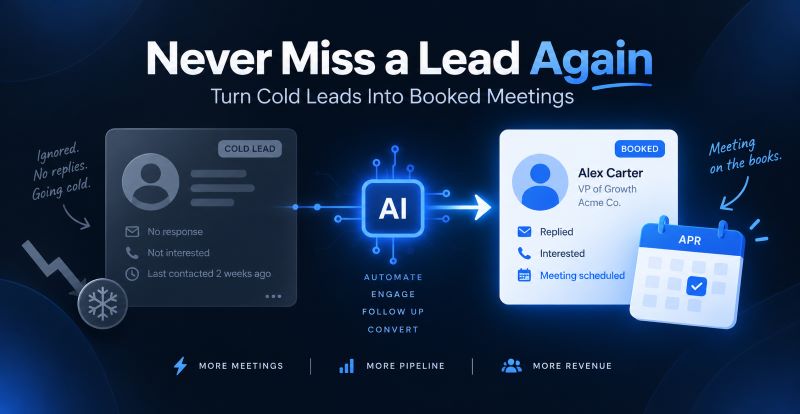
Never Miss a Lead Again: How ConvergeHub’s AI Summarizer and Momentum Indicator Turn Cold Leads Into Booked Meetings

An AI powered CRM for small business fixes the one thing that kills more deals than bad pricing or weak pitches: slow, inconsistent follow-up. Most small teams don’t lose leads because the product is wrong — they lose them because nobody replied fast enough, or nobody replied again. ConvergeHub’s AI Summarizer and Momentum Indicator are built to close exactly that gap, turning every call, email, and quiet lead into a tracked, time-stamped action instead of a forgotten browser tab.

The Real Cost of Slow Follow-Up

Before looking at the fix, it helps to see the size of the problem an AI powered CRM for small business is actually solving:

  • Firms that contact a lead within the first hour are nearly seven times more likely to have a meaningful conversation than those that wait even a few hours longer, per Harvard Business Review’s lead response research.
  • The same research found the average company took 42 hours to respond to a new lead — long after buyer interest has cooled.
  • Sales reps spend only about 30% of their week actually selling, according to Salesforce’s State of Sales report — the rest goes to admin, data entry, and follow-up coordination that a CRM should be doing automatically.
  • Sales teams already using AI saw 83% revenue growth versus 66% for teams without it, the same Salesforce report found.

What Makes This an AI Powered CRM for Small Business

A generic CRM logs what happened. An AI powered CRM for small business decides what should happen next, without a rep having to remember to check. For a lean team juggling five accounts and no dedicated SDR, that difference is the entire game: automation covers the gap that headcount would otherwise have to fill.

How the AI Summarizer Closes the Speed Gap

The AI Summarizer condenses every call transcript, email thread, and meeting note into a short, scannable summary the moment it’s captured. In practice, that means:

  • A rep can review a lead’s entire history in seconds instead of re-reading a 20-message thread before calling back.
  • Key details — budget, objections, timeline — surface automatically instead of getting buried in notes nobody reopens.
  • Follow-up emails can reference the exact point where the conversation left off, which is what actually makes a second touch land.
  • New team members can pick up a lead mid-conversation without a handoff call, since the summary carries the context.

How the Momentum Indicator Keeps Leads From Going Cold

Where the AI Summarizer handles context, the Momentum Indicator handles timing. It scores engagement velocity on every open lead and flags the exact moment a prospect starts going quiet — before the deal is dead, not after.

  • Leads are ranked by how their engagement is trending, not just their score at a single point in time.
  • A drop in reply speed, open rate, or activity automatically triggers a re-engagement task instead of waiting for a rep to notice.
  • Reps work a live shortlist of “leads losing momentum” instead of scrolling a static pipeline view guessing who to call.
  • Cold leads get a scheduled nudge sequence automatically, so a slow quarter for one rep doesn’t mean a graveyard of dead leads.

From Cold Lead to Booked Meeting: The Workflow

  • Lead comes in from a form, call, or email — logged instantly, no manual entry.
  • AI Summarizer captures and condenses the first interaction the moment it happens.
  • Momentum Indicator starts tracking engagement velocity from day one.
  • If replies slow down, a follow-up task is auto-created and assigned before the lead goes quiet.
  • Rep opens the summary, sends a context-aware follow-up, and books the meeting — without digging through old threads first.

The ROI Behind the Workflow

  • Every dollar invested in CRM returns an average of $8.71, per Nucleus Research’s CRM ROI analysis — a return that compounds further with AI-driven follow-up.
  • Teams using AI in their sales process reported 83% revenue growth this year, against 66% for teams that didn’t, per Salesforce’s State of Sales research.

For a small business without a dedicated SDR team, an AI powered CRM for small business like ConvergeHub isn’t a nice-to-have layer on top of the CRM — it’s what makes consistent, fast follow-up possible without adding headcount. Ready to see how the AI Summarizer and Momentum Indicator would work on your own pipeline? Book a demo or start a free trial.
FAQ icon showing a question mark and chat bubble, representing common questions about ConvergeHub's AI powered CRM for small business

Frequently Asked Questions

1. What is an AI powered CRM for small business?

It’s a CRM that uses AI to actively manage follow-up, scoring, and data entry — such as summarizing calls or flagging cooling leads — instead of just storing contact records for a rep to check manually.

2. How does ConvergeHub’s AI Summarizer work?

It automatically condenses call transcripts, emails, and meeting notes into a short summary the moment the interaction ends, so the key details are ready before the next touchpoint.

3. What is the Momentum Indicator?

It’s a scoring feature that tracks how a lead’s engagement is trending over time — not just a static score — and flags leads that are losing momentum so a rep can re-engage before they go cold.

4. Why does lead response time matter so much?

Leads contacted within the first hour are far more likely to turn into a real conversation than leads contacted later, per Harvard Business Review’s research, and most companies take far longer than an hour to respond.

5. Can a small business afford an AI powered CRM?

Yes — ConvergeHub is built specifically for SMB budgets and offers a 14-day free trial with no credit card required, so teams can test the AI Summarizer and Momentum Indicator before committing.

6. Does AI replace the sales rep?

No. It removes the admin and tracking work — summarizing calls, flagging cold leads — so reps spend more of their week actually selling instead of on non-revenue tasks.

7. How is this different from lead scoring in a regular CRM?

Standard lead scoring is usually a single static number. The Momentum Indicator tracks the trend in engagement over time, which catches leads that are cooling off, not just leads that scored low from the start.

8. Does the AI Summarizer work on phone calls too?

Yes — it summarizes call transcripts along with emails and meeting notes, so a rep has full context regardless of which channel the conversation happened on.

9. What happens when a lead’s momentum drops?

ConvergeHub automatically creates a follow-up task and can trigger a re-engagement sequence, so the lead gets a nudge before a rep would have otherwise noticed the silence.

10. Is this only useful for large sales teams?

It’s built for the opposite case — small teams without a dedicated SDR benefit most, since the AI covers tracking and follow-up work that would otherwise require extra headcount.

11. What kind of ROI can a small business expect?

CRM investment returns an average of $8.71 for every dollar spent, according to Nucleus Research, and businesses using AI in their sales process have reported notably higher revenue growth than those that don’t, per Salesforce’s State of Sales report.

12. How do I get started with ConvergeHub’s AI features?

Book a demo or start a 14-day free trial — both the AI Summarizer and Momentum Indicator are available on ConvergeHub’s core plans, with no credit card required to try them.
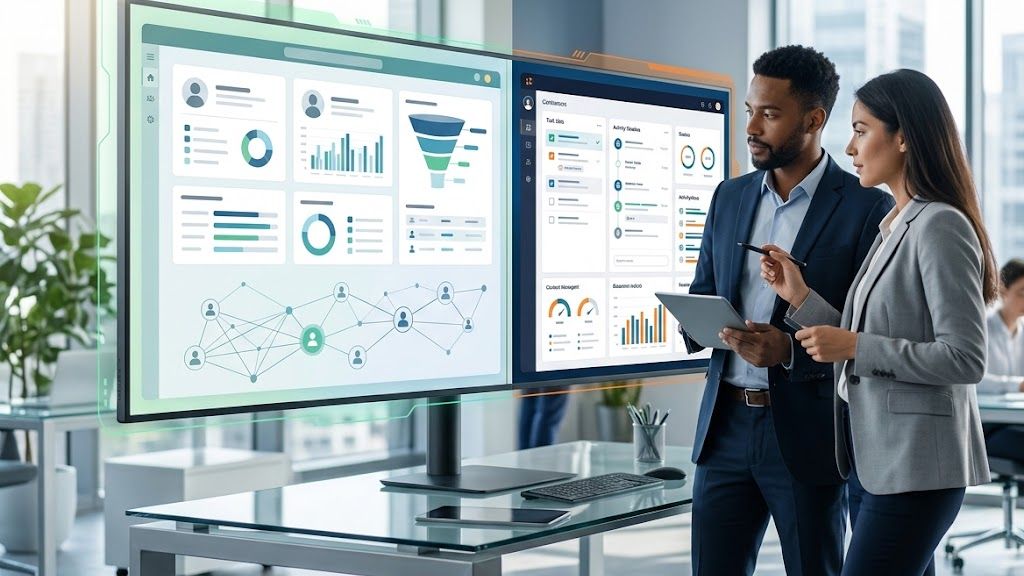
ConvergeHub vs Centrex: Which CRM Should You Choose?

ConvergeHub and Centrex Software are both MCA CRM platforms, but they are built for different jobs. Centrex is a finance-dedicated suite that pairs a CRM with loan origination, MCA servicing, syndication, and white-label portals. ConvergeHub is an all-in-one CRM that combines sales, marketing, service, and billing with an MCA edition built around inquiry-to-funding workflows. The right choice depends on whether your biggest need is running the front office or servicing a funded portfolio.

This guide compares ConvergeHub and Centrex on features, pricing, integrations, and fit, using information published by each vendor and by independent review directories as of September 2026. If you want the broader landscape first, see our roundup of the best merchant cash advance CRMs for brokers and funders.

ConvergeHub vs Centrex at a Glance

Category ConvergeHub Centrex Software
Product focus All-in-one small business CRM with a dedicated MCA edition Finance-dedicated CRM plus loan origination, servicing, and syndication tools
Best fit MCA brokers and small to mid-size funders focused on deal flow, documents, and renewals Funders, syndicates, and brokers that want servicing and syndication in the same platform
Published pricing Yes, per user per month No, pricing on request
Free trial Yes, no credit card required Demo on request; no free trial advertised
MCA deal workflow Inquiry-to-funding workflow, deal cases with owners and milestones, document checklists, offer letter tracking Multiple pipelines, one-click lender submissions, commission tracking
Lender matchmaking Not advertised Yes, lender criteria and recommendations
Underwriting support No built-in underwriting module or native bank statement or credit report integration listed; connects outside tools through its REST API and webhooks Multi-advance tracking and integrations for bank statement validation and credit reports
Servicing and syndication Billing, invoices, and payment tracking; renewal and collections reminders MCA servicing through payment processors, syndicate payouts, syndicate portal
Marketing and service Native email marketing automation, SMS, case and ticket management, knowledge base Text and email marketing
Client portal Customer portal on Premium and Enterprise plans White-labeled client portal and white-label mobile app
E-signature DocuSign integration Proprietary ClixSign e-signature
Review ratings G2 4.8/5 (36 reviews); Capterra 4.8/5 (24 reviews) Capterra, GetApp, and Software Advice 4.9/5 (8 reviews)

Ratings and review counts checked on G2 and Capterra in September 2026. Capterra, GetApp, and Software Advice share one review pool, so Centrex shows the same 8 reviews on all three.

What Is Centrex Software?

Centrex Software is a Costa Mesa, California company that sells a finance-dedicated CRM along with a wider set of white-label fintech tools, including loan origination, loan servicing, MCA servicing, syndication, a client portal mobile app, and a website form builder. Its MCA CRM is aimed at brokers, funders, and syndicates.

On its MCA page, Centrex lists pipeline management, one-click lender submissions, commission tracking, a customer portal, lender matchmaking, underwriting tools with third-party bank statement and credit integrations, deal participation tracking, and advance servicing with integrated payment processing. Its integrations page names payment processors, dialers, credit bureaus, Plaid, DecisionLogic, Twilio, and Zapier. Centrex also displays an AICPA SOC seal on its website.

What Is ConvergeHub?

ConvergeHub is an all-in-one CRM for small and mid-size businesses that combines sales, marketing, customer service, and billing in one platform. Its merchant cash advance CRM edition is designed around the way MCA shops actually work: merchant intake, document collection, offer letters, funding milestones, and renewals.

For MCA teams, ConvergeHub turns each deal into a trackable case with an assigned owner and milestones, automates document checklists and merchant reminders, tracks offer letters with an audit trail, logs every merchant interaction on one timeline, and tracks renewals and collections. Plans include custom fields, mandatory fields, role-based permissions, audit logging, a REST API, webhooks, and integrations with DocuSign, Twilio, Stripe, Outlook, Zoom, and Calendly.

Feature Comparison for MCA Teams

Deal Flow and Pipeline Management

Both platforms manage MCA pipelines. Centrex emphasizes multiple pipelines and packaging merchant files for submission to several lenders at once, which suits brokers who shop deals widely. ConvergeHub emphasizes structure inside each deal: owners, milestones, required documents, and automated follow-ups so files do not stall between inquiry and funding.

Underwriting and Lender Matching

Centrex has the edge here. It advertises lender matchmaking based on criteria you set for each funder, plus integrations for bank statement validation and credit reports. ConvergeHub does not advertise lender matchmaking or a native underwriting module, Its published integrations (DocuSign, Stripe, Twilio, Outlook, Zoom, Calendly, and AI assistants, plus a REST API and webhooks) do not include a bank statement analysis or credit report provider. Its MCA workflow does flag document gaps and check for stacking before funding, but teams that rely heavily on automated statement analysis would connect a dedicated analysis tool through the API or webhooks.

Servicing, Syndication, and Collections

Centrex also leads on post-funding operations. It lists MCA servicing through payment processors, automatic syndicate payouts, and syndicate portals. ConvergeHub covers renewals, collections reminders, invoicing, and payment tracking, which fits brokers and funders who service advances in a separate system or have simpler repayment tracking needs.

Marketing, Service, and the Merchant Relationship

ConvergeHub leads on the broader customer relationship. It includes native email marketing automation, drip sequences, SMS, case and ticket management, and a knowledge base in the same platform as the pipeline. For MCA teams that win on speed and repeat business, having outreach, support, and renewals in one record reduces the number of tools to manage. Centrex offers text and email marketing but is less focused on service and support workflows.

Customization and Adoption

ConvergeHub publishes its customization limits by plan, including custom fields, automation rules, and reports, and supports phased adoption so a team can start with intake and deal tracking and add automation later. Centrex offers extensive configuration and professional consulting services, which can suit larger operations with complex requirements. Reviewers on both platforms mention ease of use.

Pricing: ConvergeHub vs Centrex

Pricing transparency is one of the clearest differences between the two platforms.

ConvergeHub publishes its CRM pricing plans. As of September 2026, the Sales CRM plans cost $29, $45, and $59 per user per month billed annually (Professional, Premium, and Enterprise), and bundles that add marketing, service, and billing cost $59, $75, and $81 per user per month billed annually. The MCA edition is one of ConvergeHub’s industry-specific solutions, so it falls under the Industry plan, which adds guided product onboarding and white-glove premium support and is priced on request. A free trial is available with no credit card required.

Centrex Software does not publish pricing. G2 and Software Advice both list pricing as available on request, so buyers need a quote. Because Centrex offers servicing, syndication, mobile apps, and consulting as separate products, the total cost will depend on which modules you add.

Who Should Choose Centrex?

Centrex is likely the better fit if you are:

  • A funder or syndicate that wants CRM, servicing, ACH payment processing, and syndicate payouts in one vendor’s platform
  • A broker that submits most deals to many funders and wants automated lender matchmaking
  • A lender that needs a white-labeled mobile app or client portal under its own brand
  • An operation that also offers traditional loans and wants loan origination and servicing in the same suite

Who Should Choose ConvergeHub?

ConvergeHub is likely the better fit if you are:

  • An MCA broker or small to mid-size funder that loses deals to slow follow-up, missing documents, or late offer letters
  • A team that wants sales, marketing, service, and billing in one CRM instead of separate tools
  • A buyer who wants published per-user pricing and a free trial before committing
  • A shop that already services advances elsewhere and needs a front office that keeps deal flow, renewals, and merchant communication organized

Many MCA businesses run a CRM and a servicing platform side by side. If that describes your setup, compare how each option handles the work your team does every day, and look at the features MCA teams actually need before you decide.

Frequently Asked Questions

How much does Centrex Software cost?

Centrex does not publish pricing. Review directories including G2 and Software Advice list pricing as available on request, so you will need a quote based on the modules and users you need.

Does ConvergeHub offer a free trial?

Yes. ConvergeHub offers a free trial with no credit card required, and publishes per-user pricing for each plan on its website.

Is ConvergeHub or Centrex better for MCA brokers?

It depends on how you work. Brokers who submit deals to many funders may value Centrex’s lender matchmaking and submission tools. Brokers focused on faster follow-up, document collection, and renewals in an all-in-one CRM may prefer ConvergeHub.

Can ConvergeHub handle MCA servicing and syndication?

ConvergeHub tracks renewals, collections reminders, invoices, and payments, but it does not advertise syndicate payouts or payment processor servicing. Funders that need those functions typically pair it with a dedicated servicing platform.

What are the main Centrex alternatives for MCA teams?

Common alternatives include ConvergeHub, MCA Track, Cloudsquare, and general CRMs such as Salesforce and HubSpot configured for MCA workflows. The right option depends on whether you need servicing and syndication or a front-office CRM.

Which CRM is easier to adopt?

Reviewers rate both platforms highly for ease of use. ConvergeHub supports phased adoption, starting with intake and deal tracking, and publishes plan limits up front. Centrex offers consulting and training for more complex implementations.

See ConvergeHub on Your Own MCA Workflow

The best way to choose an MCA CRM is to test it against a real deal. Walk a merchant from inquiry to funding and renewal in ConvergeHub when you request a ConvergeHub demo, and compare the experience with any other platform on your shortlist.

From Lead to Closed Deal: How ConvergeHub’s Automation Engine and Pipeline IQ Cut Your Sales Cycle in Half

Most small businesses don’t lose deals because their product is wrong for the buyer. They lose deals because a lead sits in an inbox for six hours, a follow-up gets forgotten, or nobody notices a stalled opportunity until it’s too late to save. An AI-powered CRM fixes this by automating the busywork between first contact and closed deal and giving reps a clear, prioritized path through the pipeline. Here’s how ConvergeHub’s Automation Engine and Pipeline IQ work together to shorten that path.

The Real Cost of a Slow, Manual Sales Process

A manual sales process feels manageable until the pipeline grows. Then the cracks show up as missed follow-ups, inconsistent lead routing, and reps who spend more time updating records than talking to prospects.

  • Sales reps spend 60% of their time on non-selling tasks like CRM updates, internal reporting, and searching for the right information (Salesforce).
  • Leads that don’t get a fast first response cool off fast, and by the time someone follows up, the buyer has often already talked to someone else.
  • Deals stall silently. Without a system flagging inactivity, a promising opportunity can sit untouched for weeks before anyone notices.
  • Forecasts become guesswork when pipeline data lives in spreadsheets, sticky notes, and someone’s memory instead of one connected system.

How ConvergeHub’s Automation Engine Speeds Up Every Stage

The Automation Engine inside ConvergeHub’s AI-powered CRM removes the manual steps between a lead coming in and a rep actually working it.

  • New leads are captured, scored, and routed to the right rep automatically, so nothing sits unassigned.
  • Follow-up emails and task reminders trigger the moment a lead goes quiet, based on rules you set once.
  • Repetitive admin work, like logging calls or updating deal stages, happens in the background instead of eating into selling time.
  • Firms that contact a lead within an hour are roughly seven times more likely to qualify it than those that wait even one hour longer (Harvard Business Review), which is exactly the window automated routing is built to protect.

Pipeline IQ: Turning Guesswork Into a Repeatable Path to Close

Where the Automation Engine handles the busywork, Pipeline IQ handles the strategy. It gives reps and managers a live, prioritized view of what actually needs attention.

  • Deals are ranked by likelihood to close, so reps know which conversations to have first.
  • Stalled opportunities are flagged automatically instead of being discovered during a Friday pipeline review.
  • Managers get a real-time view of the entire pipeline instead of waiting on manually built weekly reports.
  • Win/loss patterns surface over time, showing which actions and touchpoints actually move deals to close.

From Lead to Closed Deal: What the Combined Workflow Looks Like

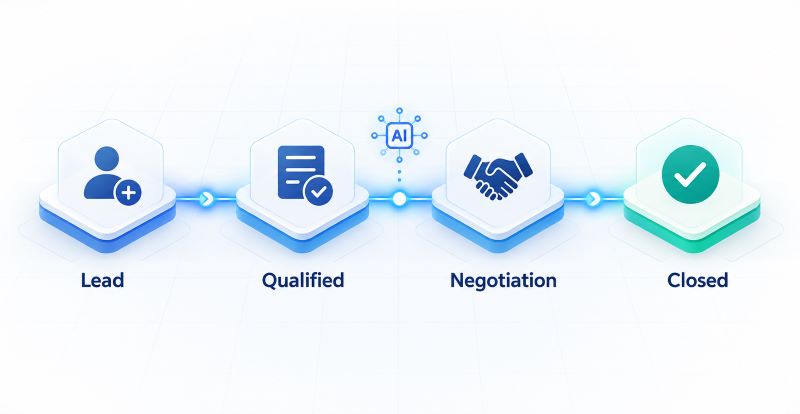
Put together, the Automation Engine and Pipeline IQ turn a scattered, manual process into a repeatable one:

  • A lead comes in and is instantly captured, scored, and assigned.
  • The assigned rep gets a task or alert to follow up immediately, inside the window that matters most.
  • Pipeline IQ tracks engagement and flags the deal if it goes cold at any stage.
  • Automated nurture sequences keep the conversation moving without requiring manual follow-up.
  • The deal moves through a prioritized pipeline view until it closes, with every touchpoint logged automatically.

The Business Impact: Shorter Cycles, Fewer Missed Deals, Higher Conversion

This isn’t a theoretical benefit. Structured, automated pipeline management shows up directly in the numbers businesses care about.

  • Well-run CRM implementations return an average of $8.71 for every $1 spent (Nucleus Research).
  • Analysts project that AI-influenced CRM spending will keep climbing as more of that spend shifts toward generative AI features by 2027 (Gartner), underscoring how central automation and AI are becoming to how CRMs are bought and used.
  • Fewer deals slip through the cracks when stalled opportunities are surfaced automatically instead of discovered too late.
  • Faster lead response and consistent follow-up directly improve the odds of turning a lead into a paying customer.
Book a free ConvergeHub demo to see the Automation Engine and Pipeline IQ in action.

Why an AI-Powered CRM Beats Spreadsheets and Manual Follow-Up

Spreadsheets and inboxes can track a handful of deals. They can’t score leads, flag stalled opportunities, or trigger a follow-up the moment a prospect goes quiet.

  • No manual data entry means fewer errors and more time for actual selling.
  • Automated scoring means reps spend their energy on the leads most likely to close.
  • A single connected system means sales, marketing, and leadership are always looking at the same numbers.
  • Nothing depends on one person remembering to follow up, so the process survives vacations, turnover, and busy weeks.

See how much time your team could get back. Start your ConvergeHub trial today.

AI powered CRM dashboard transforming a cluttered manual workflow into an organized automated workspace, with connected apps, streamlined data, and a “Book a Demo” call-to-action.

What’s the first step to reducing sales cycle length with ConvergeHub?

The first step is usually automating lead capture and first response, since that single change addresses the point where the most time and the most deals are typically lost.

A slow sales process rarely comes down to one big problem. It’s usually a string of small delays, an unassigned lead, a forgotten follow-up, a stalled deal nobody flagged, that add up to a longer cycle and lost revenue. ConvergeHub’s Automation Engine and Pipeline IQ are built to close those gaps, and an AI-powered CRM is what makes that possible without adding more work for your team.

AI-powered CRM automation accelerating sales workflows with faster follow-ups, smarter actions, and streamlined customer management.

Frequently Asked Questions

What is an AI-powered CRM?

An AI-powered CRM is a customer relationship management platform that uses automation and machine learning to score leads, trigger follow-ups, flag stalled deals, and surface pipeline insights without manual effort from the sales team.

How does ConvergeHub’s Automation Engine shorten the sales cycle?

It removes the manual delays between a lead coming in and a rep acting on it by automatically capturing, scoring, routing, and triggering follow-up tasks, so deals move faster through each stage.

What is Pipeline IQ and how is it different from a regular pipeline view?

Pipeline IQ ranks deals by likelihood to close and automatically flags stalled opportunities, giving reps and managers a prioritized view instead of a flat list of deals sorted by date.

Can automation replace the need for a sales rep to follow up personally?

No. Automation handles the timing and consistency of follow-up, like sending a reminder or nudge email, while the rep still owns the actual conversation and relationship.

How quickly should a new lead be contacted?

As close to immediately as possible. Research shows firms that contact a lead within an hour are far more likely to qualify it than those that wait even a little longer (Harvard Business Review).

Does ConvergeHub work for small businesses without a dedicated sales operations team?

Yes. The Automation Engine and Pipeline IQ are built to remove the need for a dedicated ops person by handling lead routing, follow-up, and pipeline tracking automatically.

How does an AI-powered CRM reduce missed follow-ups?

By triggering reminders and automated nurture sequences the moment a lead or deal goes inactive, instead of relying on a rep to remember to check back in.

What kind of ROI can businesses expect from a CRM investment?

Well-run CRM implementations have returned an average of $8.71 for every $1 spent (Nucleus Research), though actual returns depend on how consistently the system is used.

Does lead scoring actually improve conversion rates?

Yes. Scoring helps reps prioritize the leads most likely to convert first, instead of spending equal time on every lead regardless of fit or intent.

How does Pipeline IQ help sales managers, not just reps?

It gives managers a live, accurate view of the entire pipeline’s health, so coaching and forecasting are based on real-time data rather than a rep’s manual weekly update.

Is switching to an AI-powered CRM a big disruption for an existing sales team?

Most teams see the biggest change in what they stop doing manually. Because routing, follow-up, and reporting shift to automation, reps typically adapt quickly since it removes work rather than adding it.

UCC Filings in Merchant Cash Advance: Tracking Them in Your CRM

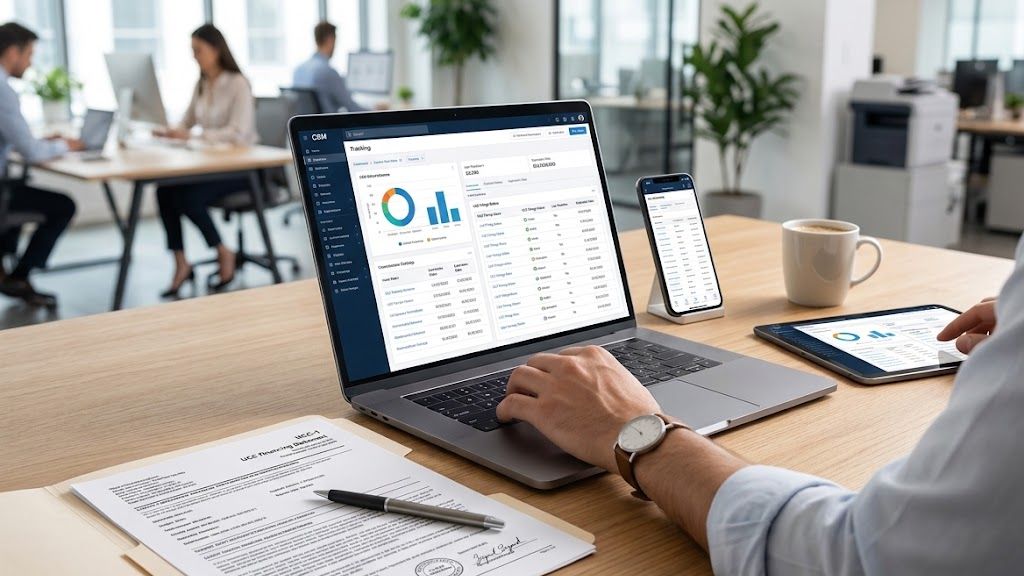
A UCC filing in a merchant cash advance is the public notice a funder files to claim an interest in a merchant’s receivables or other business assets. It protects the funder’s position against other creditors, and it has a life cycle that runs well past funding day: searches before the deal, an accurate filing at closing, a continuation if the relationship runs long, and a termination when the advance is paid. This guide explains how UCC filings work in MCA deals and how to track every stage in your CRM so none of them slip.

ConvergeHub helps MCA brokers and funders keep deals, documents, and deadlines on one record. A dedicated merchant cash advance CRM gives UCC filings a home next to the deal they secure, instead of in a separate spreadsheet that nobody updates after funding.

This article is general information, not legal advice. UCC rules are adopted state by state, so confirm filing requirements with counsel or the relevant filing office.

What Is a UCC Filing in a Merchant Cash Advance?

A UCC filing, formally a UCC-1 financing statement, is a standardized form filed with a state filing office, usually the Secretary of State, that gives public notice of a secured party’s interest in a debtor’s personal property. In an MCA, the funder is the secured party, the merchant is the debtor, and the collateral is typically the merchant’s accounts and future receivables, sometimes with a broader description covering all business assets.

The filing rules come from Article 9 of the Uniform Commercial Code, which governs secured transactions in personal property. The UCC is a joint project of the Uniform Law Commission and the American Law Institute, and every state has adopted it, with local variations. Article 9 also covers sales of accounts, which is one reason MCA funders file even though an MCA is structured as a purchase of receivables rather than a loan.

Why MCA Funders and Brokers Care About UCC Filings

UCC filings matter to MCA teams at three points in a deal:

  • Before funding: a UCC search shows which other funders and lenders already claim the merchant’s receivables, which is one of the fastest ways to spot stacking and priority problems.
  • At funding: a correctly filed UCC-1 perfects the funder’s interest and sets its priority against later creditors.
  • After funding: the filing must be continued if it needs to outlast five years and terminated once the obligation is satisfied.

Collateral position also affects collections. Under Texas HB 700, for example, automatic debits on commercial sales-based financing are restricted unless the provider holds a valid, perfected, first-priority security interest. As more states regulate MCAs, the accuracy of the UCC file carries more weight.

The UCC Filing Life Cycle in an MCA Deal

Every UCC filing on an MCA passes through the same stages. Each one has a trigger, an owner, and a record worth keeping.

Stage What happens What to record
UCC search Search the merchant’s exact legal name in its state of organization before funding Search date, results, existing secured parties
UCC-1 filing File the financing statement after the agreement is signed Filing number, filing date, filing state, collateral description
Amendment (UCC-3) Correct or update debtor, secured party, or collateral details Amendment number, date, reason
Continuation (UCC-3) Extend a filing that would otherwise lapse after five years Lapse date, continuation window, filing number
Termination (UCC-3) Release the filing after the obligation is satisfied Payoff date, termination request date, termination number

Search Before You Fund

A UCC search on the merchant’s exact legal name shows active filings and the secured parties behind them. Multiple recent filings from MCA funders often confirm what the bank statements suggest: the merchant already carries one or more positions. Compare search results with the debits on the statements, and record any secured party that has a filing but no visible payments, since that gap is worth a question before funding.

File It Accurately

A UCC-1 is only as strong as its details. For a registered organization such as an LLC or corporation, the filing generally goes to the state where the entity is organized, and the debtor name should match the name on its public formation record. A name error that keeps the filing from appearing in a standard search can leave the filing ineffective. Check the debtor name, filing state, secured party, and collateral description against the signed agreement before submitting.

Watch the Five-Year Lapse

A UCC-1 is generally effective for five years from the filing date. To keep it effective, the secured party files a UCC-3 continuation within the six months before the lapse date. Most MCAs are paid off well before five years, but renewals, long-running merchant relationships, and defaulted accounts in collection can keep a filing in play longer than expected.

Terminate When the Deal Is Done

Once an advance is paid in full and no further obligation remains, the secured party should file a UCC-3 termination. For commercial debtors, Article 9 generally requires termination within 20 days after an authenticated demand from the debtor. Stale filings frustrate merchants, show up on business credit reports, and can complicate a merchant’s next financing, including a renewal with the same funder.

Common UCC Tracking Mistakes in MCA Operations

  • Searching a trade name or DBA instead of the merchant’s exact legal name
  • Filing in the state where the merchant operates rather than the state where it is organized
  • Losing the filing number after closing, which makes later amendments and terminations slower
  • Forgetting to terminate after payoff, especially when a deal closes through a renewal
  • Assuming a renewal is covered by the old filing without checking the collateral description and lapse date
  • Leaving UCC tasks with one person, so filings stall when that person is out or leaves

How to Track UCC Filings in Your CRM

Most of these mistakes are tracking failures, and they are easiest to fix where the deal already lives. If you are still evaluating what a merchant cash advance CRM does, UCC tracking is a good test of whether a platform can handle post-funding work as well as the sales pipeline.

Store UCC Details on the Deal Record

Keep the merchant’s exact legal name, state of organization, UCC search results, filing number, filing date, lapse date, and collateral description on the same record as the deal. In ConvergeHub, admins can add custom text, list, and date fields to the Deals module, so each of these details gets its own field instead of living in notes. When a renewal, payoff, or dispute comes up, the next person on the file has every detail without digging through email.

Make the UCC Search a Required Step

ConvergeHub runs each deal as a trackable case with an assigned owner and milestones. Add the UCC search as a milestone before offer or funding so it is part of every file, and attach the search report to the deal using the same document checklist that tracks bank statements and stips.

Automate Continuation and Termination Reminders

Set reminders that fire when an advance is paid off and when a filing approaches the six-month continuation window. ConvergeHub’s automated reminders and follow-up triggers keep these tasks visible to the whole team, so a termination request or a lapse date never depends on one person’s memory.

Tie UCC Tasks to Renewals

ConvergeHub tracks renewal opportunities against the original deal record. When a merchant renews, review the existing filing’s lapse date and collateral description, decide whether it covers the new advance, and log whether it was amended, continued, or replaced. For teams growing a book through repeat funding, this is part of scaling an MCA business without losing control of the collateral file.

Keep a Clean Audit Trail

ConvergeHub’s merchant communication timeline logs calls, emails, and notes on one record. Log every UCC-related action there, from search to termination, so you can show when each step happened if a merchant, regulator, or court asks. Teams that also offer factoring, which relies heavily on UCC filings against receivables, can run the same workflow through an alternative lending CRM.

Frequently Asked Questions

Do merchant cash advance companies file UCC liens?

Many do. MCA agreements commonly authorize the funder to file a UCC-1 against the merchant’s receivables or business assets, even though the MCA is structured as a purchase of future receivables rather than a loan.

How long does a UCC filing last?

A UCC-1 financing statement is generally effective for five years from the filing date. It lapses after that unless the secured party files a UCC-3 continuation during the six months before the lapse date.

What is the difference between a UCC-1 and a UCC-3?

A UCC-1 is the original financing statement that creates the public record. A UCC-3 changes an existing filing: it can amend details, continue the filing for another five years, assign it to another party, or terminate it.

When should an MCA funder file a UCC-3 termination?

After the advance is paid in full and no further obligation remains. For commercial debtors, Article 9 generally requires termination within 20 days after the secured party receives a signed demand from the debtor. Many funders file promptly after payoff instead of waiting for a demand.

Can a UCC lien freeze a merchant’s bank account?

No. A UCC filing is a public notice of a security interest, not a court order. Freezing an account generally requires separate legal action, such as a judgment and a bank levy.

Does a renewal need a new UCC filing?

It depends on the collateral description, the agreement, and the filing’s lapse date. Review the existing filing on every renewal and confirm with counsel whether it should be amended, continued, or replaced.

Keep Every UCC Filing Attached to the Deal It Secures

UCC filings protect your position only when they are accurate, current, and closed out on time. See how ConvergeHub keeps searches, filing details, renewal reviews, and termination reminders on one deal record when you schedule a ConvergeHub demo.

Simple CRM Software: 7 Features That Actually Make a CRM Simple to Use

Simple CRM software is a customer relationship management tool built around ease of setup and daily use rather than a long list of advanced features — the goal is a system a small team can run without a dedicated CRM administrator. The word “simple” gets used loosely in CRM marketing, so it’s worth being specific about what actually makes a CRM simple versus just smaller. What’s changed recently is that an AI CRM can now deliver this same simplicity while doing more of the work automatically — lead scoring, follow-up, and routing handled by the system instead of a rep. ConvergeHub was built around that combination: full AI CRM functionality without the setup overhead that sends most small teams back to a spreadsheet. Here’s what to actually look for.

Why “Simple” Matters More Than “Full-Featured” for Small Teams

Feature-heavy CRM platforms often go underused rather than fully used. Nucleus Research’s latest analysis puts the average return at $3.10 for every dollar spent on CRM — down from a peak of $8.71 in earlier years, largely because so much licensed functionality goes unused across the industry. A small business without dedicated CRM admin support is the group most exposed to that gap: the more complex the platform, the more of it sits unused, and the return shrinks accordingly.

The alternative most small teams fall back on isn’t a competing CRM — it’s a spreadsheet. Salesforce’s own research on this found that spreadsheets typically fail as a tracking tool once a company manages more than 50 active accounts or has more than two team members touching the same file.

Simple CRM Software Meets AI CRM: 7 Features to Look For

A simple CRM exists specifically to fill that middle ground: more structure than a spreadsheet, less overhead than an enterprise platform

1. Setup That Doesn’t Require a Developer

The first real test of “simple” is whether a non-technical person can get the system running without outside help. Look for guided setup, prebuilt templates for contacts and pipelines, and no-code configuration for basic automations. If setup requires a consultant or a multi-week onboarding project, it isn’t a simple CRM regardless of what the interface looks like once it’s running.

2. Contact and Lead Management That’s Actually Centralized

A simple CRM has to solve the core problem a spreadsheet can’t: one place for every contact, note, and interaction history, updated automatically instead of manually. This is the single most important feature, since it’s the reason a business outgrows a spreadsheet in the first place — once more than a couple of people are updating the same customer record, manual tracking starts causing missed follow-ups and duplicate outreach.

3. Built-In Automation That Now Runs on AI

Simplicity doesn’t mean no automation — it means automation that doesn’t require a workflow-design background to set up. The time savings here are real: sales reps still spend 60% of their time on non-selling tasks like data entry and lead research. This is also where the line between a simple CRM and an AI CRM has started to disappear: instead of basic rule-based reminders, an AI CRM can score a lead, draft the follow-up, and decide when to send it — all configured through the same simple, no-code interface, not a separate advanced tier.

4. Fast Lead Response Without Manual Effort

Response speed has a measurable effect on outcomes regardless of company size. Research published in Harvard Business Review found that firms contacting a new lead within an hour were nearly seven times more likely to qualify it than firms that waited even one hour longer — and more than 60 times more likely than firms that waited 24 hours or more. A simple AI CRM should handle this automatically — acknowledging and scoring a new lead the moment it arrives — rather than depending on someone checking a dashboard.

5. A Clean, Uncluttered Interface

This sounds cosmetic, but it directly affects whether a team actually uses the system. If every screen shows fields, modules, and settings a small business will never touch, the CRM feels heavier than it needs to be, and adoption drops. A genuinely simple CRM shows what’s relevant to the task at hand — leads, deals, follow-ups — without burying it under enterprise-scale configuration options, even when AI features are running underneath.

6. Pricing That’s Transparent and Predictable

Complexity often shows up in pricing before it shows up in the product. A simple CRM should have a pricing structure a small business owner can explain in one sentence — not a base price plus a list of paid add-ons for basic functionality like automation, reporting, or AI features. Predictable, per-seat pricing is part of what keeps a CRM simple to manage, not just simple to use.

7. Room to Grow Without Switching Platforms

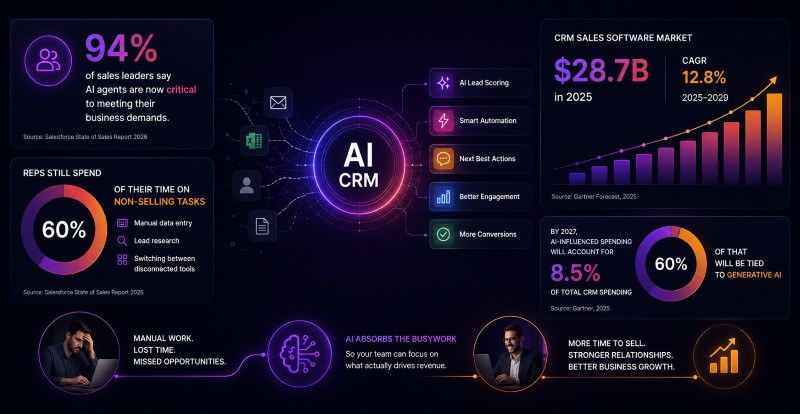
The market itself is moving toward CRMs that combine simplicity with more built-in capability, not less. Gartner forecasts the CRM sales software market growing from $28.7 billion in 2025 at a 12.8% compound annual growth rate through 2029, driven in large part by AI and automation features becoming standard rather than premium add-ons. A simple CRM chosen today should already be an AI CRM underneath — with room to turn on more automation, reporting, or AI-driven follow-up later, without forcing a migration to a completely different platform once the business outgrows the basics.

See how ConvergeHub combines all seven of these in one no-code AI CRM — most small teams are fully onboarded without outside help.

Talk to ConvergeHub about moving off spreadsheets or a CRM that’s become more work than it’s worth — most businesses can migrate existing contact data in without losing history.

Choosing a Simple CRM Software That Fits Your Team?

The right simple CRM depends less on brand and more on whether the seven features above are genuinely present or just claimed in marketing copy. A quick way to test this before committing: ask for a live setup walkthrough rather than a features list, and see how long it actually takes to get a lead into the system, scored, and a follow-up automated. If that takes more than a few minutes, the platform isn’t as simple — or as AI-driven — as it’s being sold.

The Bottom Line on Simple CRM Software

ConvergeHub was built specifically for the businesses this list describes: a centralized contact and lead system, no-code automation for follow-up and lead routing, and a clean interface that doesn’t bury day-to-day tasks under enterprise settings. As an AI CRM, it adds lead scoring, automated follow-up drafting, and churn signals on top of that same simple foundation — so the “room to grow” problem most simple CRMs eventually run into is solved before it happens. Pricing stays transparent per seat regardless of which AI features are turned on.

Simple CRM software solves a specific problem: giving a small team CRM functionality — centralized contacts, automated follow-up, fast lead response — without the setup burden of an enterprise platform. Increasingly, the platforms doing this best are AI CRMs that keep the simplicity while automating more of the actual work. The businesses getting real ROI from CRM are the ones actually using what they’ve bought, and that starts with choosing a platform simple enough to be used fully rather than partially. Book a ConvergeHub demo to see how quickly your team could be up and running.

Frequently Asked Questions

What is simple CRM software?

Simple CRM software is a customer relationship management tool designed around ease of setup and daily use, offering centralized contact management, basic automation, and lead tracking without the configuration overhead of enterprise CRM platforms.

How is a simple CRM different from a regular CRM?

The core functions are similar — contact management, lead tracking, follow-up. The difference is in setup and interface: a simple CRM is built to be configured and used by a non-technical team without a dedicated administrator.

Is a simple CRM the same thing as an AI CRM?

Not always, but the best simple CRMs are increasingly built as AI CRMs — combining an easy, no-code setup with automated lead scoring, follow-up, and churn alerts, rather than treating AI as a separate advanced tier.

Is a simple CRM only for very small businesses?

No. Simple CRM software works for solopreneurs and small teams, but many platforms — including ConvergeHub — are built to scale into more advanced AI-driven automation and reporting as the business grows, without requiring a switch to a different system.

Can a simple CRM replace a spreadsheet?

Yes, and for most growing businesses it should. Spreadsheets typically become unreliable once more than a couple of people are updating the same file or the contact list passes a few dozen active accounts.

Does a simple CRM include automation?

Yes. The distinction isn’t the absence of automation — it’s automation, including AI-driven lead scoring and follow-up, that can be set up without technical expertise through a visual interface.

How long does it take to set up a simple CRM?

Most simple CRM platforms are designed for same-day setup, with guided onboarding and prebuilt templates for contacts, pipelines, and basic automations.

Will a simple CRM handle lead follow-up automatically?

Yes. A key feature of simple, AI-driven CRM software is automated lead acknowledgment and follow-up, so a new lead gets a response immediately rather than waiting for a rep to notice it.

Is simple CRM software more affordable than enterprise CRM platforms?

Generally, yes. Simple CRM platforms are typically priced with transparent, predictable per-seat pricing rather than a base fee plus paid add-ons for standard functionality or AI features.

How do I know if a CRM is actually simple or just marketed that way?

Ask for a live walkthrough of setup rather than a feature list, and time how long it takes to add a contact, build a pipeline, and automate a follow-up. If it takes more than a few minutes without help, it isn’t genuinely simple — regardless of how much AI it claims to have.

MCA Compliance: Tracking State Disclosure Requirements in Your CRM

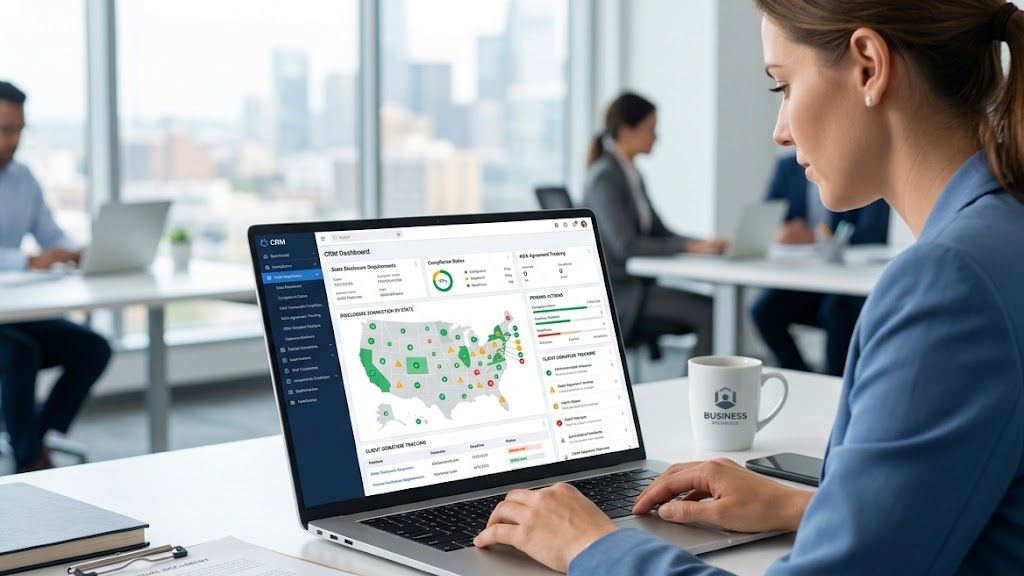
Merchant cash advance disclosure requirements now apply in eleven states, and a twelfth law is scheduled to take effect in 2027. Each state sets its own dollar thresholds, disclosure fields, and registration rules, so a broker or funder working across state lines needs a reliable way to know which rules apply to each deal. This guide covers which states have MCA disclosure laws, what a compliant disclosure typically includes, and how to track every requirement inside your CRM.

ConvergeHub helps MCA brokers and funders keep deal steps, documents, and offer letters in one system. Compliance works best when it is built into that same workflow, which is why a dedicated merchant cash advance CRM is a practical place to manage state disclosure rules.

This article is general information, not legal advice. State laws and regulations change, so confirm current requirements with qualified counsel or the relevant state regulator before relying on them.

What Are Merchant Cash Advance Disclosure Requirements?

Merchant cash advance disclosure requirements are state laws that require providers, and in some states brokers, to give a business a standardized written summary of the cost and terms of a financing offer before the deal is signed. Because an MCA is structured as a purchase of future receivables rather than a loan, it has historically fallen outside federal Truth in Lending Act disclosures. State commercial financing disclosure laws fill that gap for sales-based financing and, in many states, for other commercial products such as factoring and small business loans.

These laws regulate transparency, not price. Most do not cap factor rates or fees. They focus on making sure a merchant can see the real cost of an offer and compare it with other options.

Which States Have MCA Disclosure Laws?

As of September 2026, eleven states have enacted commercial financing or sales-based financing disclosure laws that can cover merchant cash advances. Coverage depends on the merchant’s location, the financing amount, the product type, and whether the provider qualifies for an exemption.

State Coverage limit Estimated APR required? Registration In effect
California $500,000 or less Yes No; annual report to DFPI by March 15 Dec 9, 2022 (SB 362 updates Jan 1, 2026)
New York $2.5 million or less Yes None under the CFDL Aug 1, 2023
Utah $1 million or less No Providers register Jan 1, 2023
Virginia $500,000 or less (sales-based) No Providers and brokers register 2022
Florida $500,000 or less No No Jan 1, 2024
Georgia $500,000 or less No No Jan 1, 2024
Connecticut $250,000 or less (sales-based) No Providers register annually Jul 1, 2024
Kansas $500,000 or less No No Jul 1, 2024
Missouri $500,000 or less No Brokers register 2025
Texas Under $1 million (sales-based) No Providers and brokers by Dec 31, 2026 Sep 1, 2025
Louisiana No dollar cap (revenue-based) No No Aug 1, 2025

Two more developments are worth tracking. Vermont enacted Act 142 in June 2026, which brings sales-based financing and factoring under a licensing and disclosure framework starting July 1, 2027. New Jersey has disclosure bills pending but, as of this writing, no enacted law. Teams that offer factoring or revenue-based financing alongside MCAs should note that several of these laws reach those products too, which is where an alternative lending CRM with configurable deal types helps.

What Must an MCA Disclosure Include?

Formats differ by state, but most MCA disclosures must show the merchant some combination of the following before the deal closes:

  • Total amount of financing and the amount actually disbursed after fees
  • Finance charge, meaning the total dollar cost of the financing
  • Total repayment amount
  • Estimated APR, in states such as California and New York
  • Payment method, frequency, and amount, or an estimate for sales-based payments
  • Estimated term
  • Prepayment policy, including whether early payoff reduces the cost
  • Broker compensation, where the state requires it
  • For renewals or refinances, how much of the new funding pays off the existing balance

Estimated APR is usually the hardest field for MCA providers, because an advance has no fixed term. States that require it prescribe how to estimate the term and payment schedule, so the calculation method should be documented and applied the same way on every offer.

Where MCA Disclosure Compliance Breaks Down

Most compliance gaps are process gaps, not knowledge gaps. The common failure points are:

  • Using the broker’s or funder’s state instead of the merchant’s state to decide which law applies
  • Missing a threshold, such as Connecticut’s lower $250,000 limit or New York’s higher $2.5 million limit
  • Sending an outdated disclosure template after a state updates its rules
  • Treating a renewal or refinance as exempt when a new disclosure is required
  • Failing to prove which disclosure the merchant received and when they signed it
  • Losing track of registration renewals and reporting dates across several states

Each of these is a tracking problem. Spreadsheets and inboxes rarely show, at a glance, which state rules apply to a deal and whether every required step has been completed.

How to Track State Disclosure Requirements in Your CRM

A CRM does not replace legal review or a compliant disclosure template. It makes sure the right template goes out on the right deal at the right time, and that you can prove it later. These seven steps turn disclosure rules into a repeatable workflow.

1. Capture the Merchant’s Governing State at Intake

Record the state where the merchant’s business is principally directed or managed on the deal record at the first touch. That single field decides which disclosure law, if any, applies, so make it required from the start. In ConvergeHub, an admin can add this as a custom list field on the Deals module and set it as mandatory, so a deal record cannot be created or updated without it.

2. Record the Product Type and Financing Amount

Store whether the offer is a merchant cash advance, revenue-based financing, factoring, or a loan, along with the offer amount. Several laws apply only to sales-based financing, and every state except Louisiana has a dollar cap, so these two fields let your team test coverage in seconds.

3. Maintain a State Rules Reference

Keep one internal reference, reviewed by counsel, that lists each state’s threshold, required fields, APR rule, and registration status. Link it from the deal workflow so reps and underwriters check the same source instead of relying on memory. Update it whenever a state changes its rules, and note the review date.

4. Tie the Disclosure to the Offer Letter Step

ConvergeHub lets teams send, sign, and track offer letters inside the CRM with a complete audit trail. Add the state disclosure to that same milestone so an offer cannot move to funding until the disclosure is delivered and acknowledged. When the disclosure and offer share one step, the file never has one without the other. These are the kinds of workflow features MCA teams actually need from a CRM.

5. Log the Signed Disclosure and Its Version

Store the signed disclosure on the deal record with the template version, the date it was sent, and the date it was signed. ConvergeHub’s merchant communication timeline keeps every interaction on one record, so a reviewer can see exactly what the merchant received. Retain these records for the period your counsel recommends.

6. Re-Trigger Disclosures on Renewals and Refinances

ConvergeHub tracks renewal opportunities against the original deal record. Build a rule that treats every renewal or refinance as a new offer requiring a fresh disclosure, including the amount used to pay off the existing balance where the state requires it. Texas, for example, requires that payoff information on renewal financing.

7. Track Registration and Reporting Deadlines as Tasks

Registration and reporting dates are easy to miss because they happen once a year. Create recurring tasks with owners for each obligation, such as California’s March 15 annual report, Connecticut’s annual registration, and Texas’s December 31, 2026 registration deadline. Texas registration runs through NMLS, the licensing platform that the Conference of State Bank Supervisors owns and operates on behalf of state regulators. Automated reminders keep these dates visible to the whole team instead of one person’s calendar.

Texas also limits automatic debits unless the provider holds a first-priority perfected security interest. Because most MCA remittances run as ACH debits governed by operating rules that Nacha develops and administers, collection setup is worth reviewing alongside the disclosure workflow.

Protecting Disclosure Records in Your CRM

Disclosure files contain financing terms, bank details, and owner information, so they deserve the same protection as any sensitive customer data. Limit access by role, require strong authentication, and keep records in one secure system instead of shared drives and email attachments. Review your CRM security practices for storing customer data before moving compliance records into any platform.

Frequently Asked Questions

Which states require an APR disclosure for merchant cash advances?

California and New York require an estimated APR in their commercial financing disclosures. Most other disclosure states require cost, repayment, and payment terms without an APR. Vermont’s Act 142, effective July 1, 2027, will also require an estimated APR on every specific offer.

Do MCA brokers have to register with the state?

In some states, yes. Virginia, Connecticut, and Texas require both providers and brokers to register, Missouri requires broker registration only, and Utah requires provider registration. Starting July 1, 2027, Vermont will require providers and brokers to be licensed. Requirements depend on your role in the transaction.

When is the Texas HB 700 registration deadline?

Providers and brokers of commercial sales-based financing in Texas must register with the Office of Consumer Credit Commissioner by December 31, 2026, and renew annually. The law’s disclosure requirements took effect September 1, 2025.

Do disclosure laws apply to MCA renewals?

In most disclosure states, a renewal or refinance is a new financing offer that requires a new disclosure. Some states also require showing how much of the new funding pays off the prior balance.

Is a merchant cash advance a loan?

An MCA is generally structured as a purchase of future receivables rather than a loan, which is why it falls outside many lending laws. State disclosure laws still apply to MCAs when the transaction meets their coverage rules.

Can a CRM make my MCA business compliant?

A CRM cannot replace legal advice or a compliant disclosure template. It helps by capturing the right data at intake, attaching the correct disclosure to each offer, recording signatures, and tracking renewals and registration deadlines.

Make Disclosure Compliance Part of Every Deal

State disclosure rules are multiplying, and the teams that keep up are the ones that build them into daily deal flow. See how ConvergeHub keeps offer letters, documents, renewals, and deadlines on one record when you book a ConvergeHub demo.

How to Analyze Bank Statements for MCA Underwriting

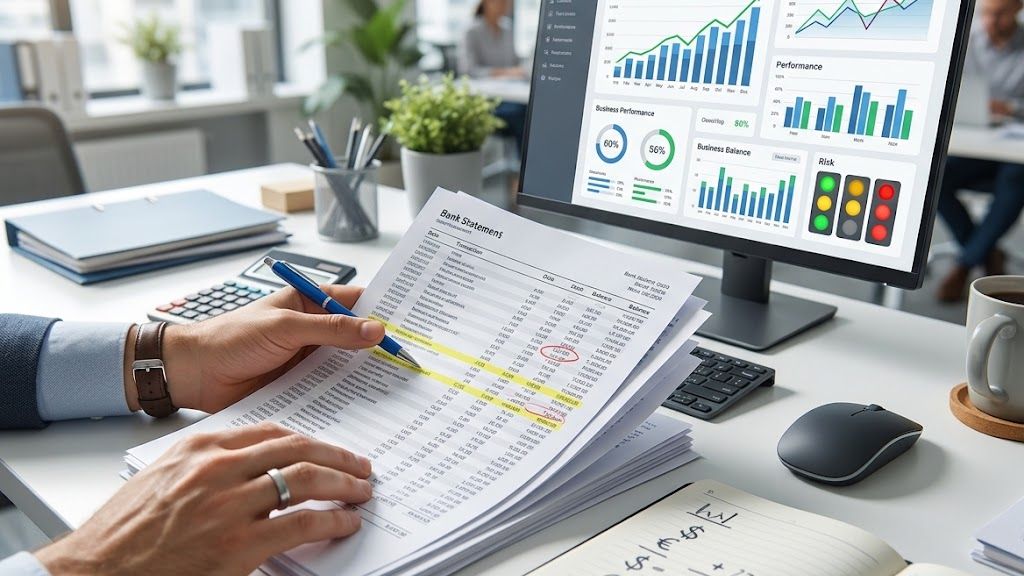
Bank statement analysis is the core of merchant cash advance underwriting. Because an MCA is repaid from daily or weekly deposits, the business bank statement tells a funder more about repayment ability than a credit score or a tax return does. This guide walks MCA brokers, ISOs, and funders through a seven-step method for reading statements, the math behind true revenue and burden, the red flags that should pause a deal, and how an MCA CRM keeps the analysis consistent from submission to renewal.

ConvergeHub works with MCA teams that want statement review, stipulations, and funding steps in one system instead of scattered spreadsheets and email threads. The method below works with any underwriting tool, and it gets faster when every file follows the same checklist inside a dedicated MCA CRM.

What Is Bank Statement Analysis in MCA Underwriting?

Bank statement analysis in MCA underwriting is the review of a merchant’s business bank transactions to measure true revenue, cash cushion, existing financing obligations, and document integrity before a funder purchases a share of future receivables. An MCA is structured as a purchase of future receivables rather than a loan, so there is usually no collateral or amortization schedule to fall back on. The cash flow in the account is the underwriter’s main protection.

That is why an MCA file looks different from a bank credit memo. Personal credit often works as a screening filter, while the statements decide the advance size, the holdback or fixed remittance, the factor rate, and the term.

Which Documents and How Many Months of Statements Do You Need?

Most MCA funders ask for three to six months of business bank statements for a first position, and many request a longer history for larger advances or seasonal businesses. A typical submission package includes:

  • Three to six months of complete business checking statements from every operating account the merchant uses
  • Merchant processing statements when card sales make up a large share of revenue
  • A signed application with legal entity name, time in business, industry, and requested amount
  • Owner ID and a voided business check or other bank verification
  • A month-to-date statement, often requested as a stipulation just before funding

Three months shows current performance. Six to twelve months shows seasonality, which matters for landscaping, construction, retail, and other businesses with strong peaks and slow periods.

How to Analyze Bank Statements for MCA Underwriting: 7 Steps

The most reliable way to analyze bank statements for MCA underwriting is to run the same seven steps on every file:

  1. Confirm the statement set is complete and genuine
  2. Calculate true revenue
  3. Measure deposit frequency and consistency
  4. Review daily balances, NSFs, and negative days
  5. Identify existing positions and stacking
  6. Calculate the MCA burden
  7. Summarize the file and assign a risk grade

Step 1: Confirm the Statement Set Is Complete and Genuine

Start by checking that every month and every page is present, that the account holder name matches the application, and that the balances reconcile. Beginning balance plus credits minus debits should equal the ending balance, and each month’s ending balance should match the next month’s opening balance. A broken balance chain, missing pages, mismatched fonts, or a PDF that shows signs of editing is a reason to request a bank-verified copy or a direct bank connection before going further.

Step 2: Calculate True Revenue

True revenue is the merchant’s real sales income after removing every credit the business did not earn from customers. It sets the maximum advance size, and gross deposits almost always overstate it.

Credit type Count as true revenue? Reason
Card processor settlements Yes Sales income
Customer ACH payments, checks, and wires Yes Sales income
Transfers from the merchant’s other accounts No The same money moving between accounts
MCA or loan proceeds No Financing that carries its own repayment
Refunds, reversals, and chargeback credits No Reverses an earlier transaction
Owner capital injections No Owner funding, not business performance
Tax refunds and insurance payouts No One-time and non-recurring

Record gross deposits and true revenue side by side for each month, with a note on what was excluded and why. That note lets a second reviewer or a funder check the work instead of redoing it.

Step 3: Measure Deposit Frequency and Consistency

Count deposit days per month and compare true revenue month over month. Daily remittance works best when deposits land on most business days, not in one or two large lumps. A merchant with steady true revenue is usually a stronger file than one whose higher average rests on a single strong month. Many underwriters also compare 30, 60, and 90 day averages and size the offer on the most conservative figure.

Step 4: Review Daily Balances, NSFs, and Negative Days

The average daily balance shows whether the account holds enough cash between deposits to absorb a daily or weekly debit. Track it alongside the lowest balance in each month, the number of negative-balance days, and the count of NSF or returned items.

NSFs and negative days measure different things. An NSF means a payment bounced or was returned, while a negative day means the account dipped below zero and recovered, often through overdraft coverage. Most MCA remittances move over the ACH Network, whose operating rules are developed and administered by Nacha, so a failed funder debit usually appears on the statement as a returned ACH item with a fee. A pattern of returned debits to a funder signals that the merchant is already struggling to carry an existing position.

Step 5: Identify Existing Positions and Stacking

An existing position is an active advance the merchant is still repaying. Positions appear as equal debits on a fixed daily or weekly rhythm, usually to a lender-like payee. Group every debit by payee across the full statement period, then apply a cadence check: fixed daily or weekly debits usually indicate an MCA, while monthly debits usually indicate a term loan or equipment note.

MCA stacking is when a merchant takes a new advance while earlier ones are still being repaid. Watch for a large funding credit followed by a new recurring debit, since that shows a position opened during the statement window. A new payee with only one or two debits should be flagged for review rather than counted, because its rhythm is not established yet.

Step 6: Calculate the MCA Burden

MCA burden is the share of true revenue already committed to financing payments. Add all position payments for the month and divide by true revenue, not gross deposits. Here is an illustrative example:

  • Gross deposits: $90,000
  • Excluded credits (an $8,000 owner transfer and a $2,000 reversed payment): $10,000
  • True revenue: $80,000
  • Existing positions: Funder A at $600 per business day and Funder B at $400 per business day, $1,000 per day combined
  • Monthly debt service at 21 business days: $21,000
  • Burden on true revenue: $21,000 ÷ $80,000 = 26.3%
  • Burden on gross deposits: $21,000 ÷ $90,000 = 23.3%, which understates the pressure
  • Burden after a proposed $500 daily position: $31,500 ÷ $80,000 = 39.4%

Every funder sets its own threshold, but burden that climbs toward half of true revenue generally signals serious repayment pressure. The figure you report should always state which denominator you used.

Step 7: Summarize the File and Assign a Risk Grade

Finish with a short, sourced summary instead of a transaction dump. A useful underwriting summary covers monthly true revenue with exclusions, deposit days, average daily balance, NSF and negative-day counts, existing positions with daily payment amounts, burden before and after the proposed advance, document-integrity findings, and open questions for the merchant. Many funders then map the file to an internal paper grade, commonly A through D, that drives advance size, factor rate, and term.

Red Flags That Should Pause an MCA Deal

Some findings should pause a deal until the merchant or broker explains them:

  • Missing months or pages in the statement set
  • Balance math that does not reconcile, or signs a PDF was edited after the bank issued it
  • Round-number deposits with no processor or customer descriptor, especially just before the application date
  • A sharp revenue spike in the most recent month
  • Heavy transfer activity inflating gross deposits
  • Repeated NSFs or returned funder debits
  • Funder debits that do not appear on the application
  • Heavy deposit concentration from a single customer

None of these proves fraud on its own. Each one is a reason to request verification and record the answer on the file.

Manual Review vs Automated Bank Statement Analysis

Manual review with a spreadsheet can be accurate, but it is slow and depends heavily on the individual underwriter. Automated bank statement analysis tools parse transactions, group debits, and run the math in minutes, which frees the underwriter to focus on judgment calls.

Factor Manual review Automated analysis
Speed Line-by-line entry on every file Transactions parsed in minutes
Consistency Varies by reviewer and workload Same rules applied to every file
Stacking detection Easy to miss a small daily debit Debits grouped by payee and cadence
Audit trail Notes in a spreadsheet Figures linked to source transactions
Final decision Underwriter Still the underwriter

The practical model is software for extraction and math, and people for the decision.

How an MCA CRM Turns Statement Analysis Into a Repeatable Workflow

Analysis tools read the statement. An MCA CRM manages everything around it: who requested the statements, what is still missing, where the summary lives, and what happens next. If you are still weighing what a merchant cash advance CRM does, this is the part of the process where the difference shows most clearly.

Standardize Statement Collection and Stips

ConvergeHub creates a document checklist for each deal and sends automated reminders when bank statements, processing statements, or month-to-date stips are missing, so files reach underwriting complete.

Keep the Underwriting Summary on the Deal Record

Each deal in ConvergeHub is a trackable case with an assigned owner, milestones, and a full communication timeline. Storing true revenue, burden, position count, and red-flag notes on that record [CLIENT TO CONFIRM: custom fields for underwriting metrics] means the next reviewer sees the same numbers and the reasoning behind them. Shared visibility like this is central to the features MCA teams actually need from a CRM.

Hand Off Cleanly From Broker to Funding

Milestone alerts show when a file moves from submission to underwriting, offer letter, stips, and funding. Offer letters can be sent, signed, and tracked inside the CRM with a complete audit trail, so nobody chases status updates by email.

Reuse the Analysis at Renewal

ConvergeHub tracks renewal opportunities against the original deal record. When a merchant returns, the earlier statement summary gives the underwriter a baseline for comparing revenue trend, balance behavior, and positions, which matters for any team focused on growing an MCA business through repeat funding.

Frequently Asked Questions

How many months of bank statements do MCA underwriters review?

Most MCA underwriters review three to six months of business bank statements, and many ask for a month-to-date statement before funding. Larger advances and seasonal businesses often require six to twelve months so the underwriter can see slow periods as well as peaks.

What is true revenue in MCA underwriting?

True revenue is the merchant’s actual sales income after removing transfers between the merchant’s own accounts, loan or MCA proceeds, refunds, reversals, owner injections, and one-time credits. It is the correct base for sizing an advance and calculating burden.

What is a good MCA burden percentage?

There is no single industry standard, and each funder sets its own limit. Lower burden means more room for a new position, and burden approaching half of true revenue generally signals significant repayment pressure. Always calculate it on true revenue rather than gross deposits.

How do underwriters detect MCA stacking?

Underwriters group every debit by payee and look for fixed daily or weekly payments to lender-like counterparties. They also watch for large funding credits followed by new recurring debits, which show a position opened during the statement period.

Do MCA underwriters check credit scores?

Many run a soft credit check as a screening step, but credit carries less weight than cash flow. Because repayment comes from daily or weekly deposits, the bank statements usually decide the file.

Build a Consistent Underwriting Workflow With ConvergeHub

Careful bank statement analysis wins more deals when every file follows the same steps and every result lands in one place. See how ConvergeHub organizes statements, stips, offer letters, and renewals for MCA teams when you request a ConvergeHub demo.

AI CRM vs Traditional CRM: 7 Signs Your Small Business Has Outgrown Manual Tracking

An AI CRM differs from a traditional CRM in one core way: a traditional CRM is a passive system that only reflects what a rep manually enters, while an AI CRM actively scores leads, drafts follow-up, and flags at-risk deals on its own. Most small businesses don’t decide to switch because of a feature list — they switch because specific, recognizable cracks start showing in how the team tracks customers day to day. ConvergeHub’s AI CRM was built to catch exactly those cracks before they cost a deal. Let’s delve more in the following piece.

How Do You Know When It’s Time to Move from Manual Tracking to an AI CRM?

Here are the signs worth watching for, and what the data says about making the move.

Sign 1: Leads Are Sitting Untouched for Hours

In a traditional CRM, a new lead is just a new row — nothing happens until a rep notices it. That delay is expensive. Research published in Harvard Business Review found that firms contacting a new lead within an hour were nearly seven times more likely to qualify it than firms that waited even one hour longer — and more than 60 times more likely than firms that waited 24 hours or more. An AI CRM removes this gap entirely by scoring and acknowledging a lead the moment it arrives, regardless of who’s available.

Sign 2: Your Team Is Still Living in Spreadsheets

A lot of small businesses start with a spreadsheet, and that’s fine — until it isn’t. Salesforce’s own research on this transition point found that spreadsheets typically fail as a tracking tool once a company manages more than 50 active accounts or has more than two team members touching the same file, since version conflicts and manual updates start actively slowing down response times past that point. An AI CRM replaces that single shared file with a live, automatically updated system no one has to reconcile by hand.

Sign 3: Follow-Up Is Generic Because Personal Follow-Up Doesn’t Scale

A small team can personalize outreach for a handful of leads, but not hundreds. The problem is that customers increasingly notice the difference: 73% of B2B buyers actively avoid vendors who send irrelevant outreach. A traditional CRM can’t fix this because it doesn’t generate the follow-up — a person still has to write it. An AI CRM pulls from a contact’s actual history to draft personalized outreach automatically, at a volume no individual rep could sustain.

Sign 4: Reps Spend More Time on Admin Than Selling

This is one of the clearest, most measurable signals. Sales reps still spend 60% of their time on non-selling tasks — manual data entry, lead research, and switching between disconnected tools. A traditional CRM doesn’t reduce this; it’s usually part of the problem, since every update depends on a rep remembering to log it. An AI CRM logs, scores, and routes automatically, which is where the time actually gets returned to selling.

Sign 5: Nobody Notices a Customer Has Gone Quiet Until It’s Too Late

In a traditional CRM, churn risk only becomes visible after a renewal is missed or a customer explicitly cancels — the system has no way to flag it earlier. An AI CRM tracks engagement patterns continuously and surfaces a cooling account while there’s still time to act on it, rather than after the fact.

Sign 6: Your Market Has Already Started Moving This Direction

This isn’t just an internal efficiency question — it’s increasingly the market standard. 94% of sales leaders now say AI agents are critical to meeting business demands, and Gartner forecasts the CRM sales software market growing from $28.7 billion in 2025 at a 12.8% compound annual growth rate through 2029, driven largely by AI functionality moving from optional to expected. A small business relying on a traditional CRM isn’t just working harder than it needs to — it’s falling behind where the category itself is headed.

Sign 7: You’re Paying for CRM Software but Not Seeing the Return

CRM has always delivered strong ROI on paper, but that return depends entirely on whether the system is actually used, not just purchased. Nucleus Research’s latest analysis puts the average return at $3.10 for every dollar spent on CRM — down from a peak of $8.71 in earlier years, largely because so much licensed functionality goes unused. A traditional CRM depends on a rep remembering to use every feature correctly. An AI CRM builds the highest-value actions — scoring, follow-up, alerts — into the system by default, so the return isn’t dependent on discipline alone.

See how ConvergeHub’s AI CRM addresses each of these signs automatically — most small businesses recognize at least three or four from this list before they’ve even started evaluating a switch.

What Actually Changes When You Move to an AI CRM

The shift isn’t just “more automation” in the abstract — it changes specific, everyday friction points:

  • Lead response moves from whenever-a-rep-notices to immediate, at any hour.
  • Follow-up moves from manually drafted to automatically personalized at scale.
  • Data entry moves from a rep’s responsibility to something the system handles by default.
  • Churn signals move from after-the-fact to early and actionable.
  • Reporting moves from a manual spreadsheet pull to a live, always-current view.

Talk to ConvergeHub about moving your team off manual tracking — most businesses can migrate existing contact and pipeline data without losing history in the process.

Making the Switch Without Losing What Already Works

Switching from a traditional CRM (or a spreadsheet) doesn’t mean starting over. The businesses that make this transition smoothly tend to do three things: migrate existing data before turning on automation, start with one or two workflows (like lead scoring or follow-up) rather than automating everything at once, and keep the human relationship-building work — negotiation, complex problem-solving — with the rep, letting the AI CRM handle the repetitive layer underneath it.

AI CRM vs Traditional CRM comes down to one question — visual comparing automated intelligence against manual tracking for small businesses

AI CRM vs Traditional CRM Comes Down to One Question

The difference between an AI CRM and a traditional CRM isn’t a longer feature list — it’s whether the system acts on your data or just stores it. For a small business, that distinction determines whether leads get contacted in minutes or hours, whether follow-up is personal or generic, and whether a cooling customer relationship gets caught in time. Book a ConvergeHub demo to see which of these signs apply to your team right now.

Frequently Asked Questions

What is the main difference between an AI CRM and a traditional CRM?

A traditional CRM stores data that a team enters manually and reports on what already happened. An AI CRM actively scores leads, drafts follow-up, and flags at-risk deals based on that same data, without waiting for a rep to review it.

How do I know if my business has outgrown a traditional CRM or spreadsheet?

Common signs include leads sitting untouched for hours, more than two people editing the same tracking file, follow-up that’s become generic because there’s no time to personalize it, and reps spending more time on data entry than actual selling.

Is switching to an AI CRM disruptive for a small team?

Not if it’s done in stages. Migrating existing contact and pipeline data first, then turning on one or two automated workflows at a time, avoids the disruption of trying to automate everything at once.

Will an AI CRM work with the data currently sitting in spreadsheets?

Yes. Most AI CRM platforms, including ConvergeHub, can import existing spreadsheet or legacy CRM data, so a business doesn’t lose contact history or deal records in the switch.

Does an AI CRM replace the need for sales reps?

No. It removes repetitive tasks like data entry, initial lead response, and follow-up drafting, so reps spend more time on negotiation and relationship-building rather than administrative work.

How much time does a small business typically waste on manual CRM tasks?

Industry research shows sales reps spend roughly 60% of their time on non-selling tasks like data entry and lead research — time an AI CRM largely reclaims through automation.

Is an AI CRM more expensive than a traditional CRM?

Not necessarily. Many AI CRM platforms built for small businesses include AI features in standard pricing rather than charging extra, and the time saved often offsets the cost difference within the first few months.

What happens to lead response time with an AI CRM?

An AI CRM can acknowledge and begin scoring a new lead within seconds of it arriving, at any hour, compared to a traditional CRM where a lead waits until a rep is available to review it.

Can an AI CRM catch a customer who’s about to churn?

Yes. Unlike a traditional CRM, which only shows churn after it happens, an AI CRM tracks engagement patterns continuously and can flag a cooling account early enough for a rep to intervene.

Is a traditional CRM still a reasonable choice for a very small business?

It can work temporarily for a handful of contacts, but most businesses hit friction once they cross a few dozen active accounts or add a second person to the same tracking system — the point where manual updates start causing missed follow-ups.

AI CRM: How ConvergeHub Turns Small Business Engagement Into Revenue

An AI CRM is a customer relationship management platform that uses artificial intelligence to score leads, automate follow-up, and recommend next steps instead of just storing contact records. For a small business, that difference matters more than it sounds: it closes the gap between a five-person team and a competitor with a dedicated sales operations department. ConvergeHub’s AI CRM was built for exactly that gap, turning a static database of names into a system that actively drives engagement, retention, and revenue. Here’s what’s changed, what the data shows, and how to choose the right platform.

What Is an AI CRM, and How Is It Different From a Traditional CRM?

A traditional CRM records what happened. An AI CRM decides what should happen next — scoring a lead, drafting a follow-up, or flagging a customer who’s gone quiet — without a rep having to dig through the database first.

The practical differences show up in daily use:

  • Lead handling: a traditional CRM logs a new lead; an AI CRM scores it, routes it to the right rep, and drafts the first response automatically.
  • Follow-up: a traditional CRM reminds a rep to follow up; an AI CRM writes the follow-up and times it for when the customer is most likely to engage.
  • Forecasting: a traditional CRM shows historical pipeline data; an AI CRM predicts which deals are at risk before they stall.
  • Customer insight: a traditional CRM stores notes; an AI CRM summarizes every interaction into a next-best-action recommendation.

See how ConvergeHub’s AI CRM automates this from the first lead touch — the platform is built around this exact shift from passive record-keeping to active engagement.

Why small business engagement is changing so fast with AI CRM adoption

Why Small Business Engagement Is Changing So Fast

The push toward AI CRM isn’t a marketing trend — it shows up directly in how sales and service teams now operate. 94% of sales leaders say AI agents are now critical to meeting their business demands, a sharp jump from a few years ago when AI in CRM was still considered experimental.

Part of the reason is where reps’ time actually goes. Sales reps still spend 60% of their time on non-selling tasks — manual data entry, lead research, and switching between disconnected tools — which is precisely the work an AI CRM is built to absorb.

The spending data backs this up at the market level. Gartner forecasts the CRM sales software market growing from $28.7 billion in 2025 at a 12.8% compound annual growth rate through 2029, driven largely by generative AI and AI sales agents expanding what CRM platforms do. Separately, Gartner projects that by 2027, AI-influenced spending will account for 8.5% of total CRM spending, with 60% of that tied to generative AI specifically. Small businesses adopting AI CRM now are moving with the market, not ahead of it.

AI CRM adoption driving faster small business customer engagement

How AI CRM Actually Improves Small Business Engagement

The clearest advantage of an AI CRM isn’t a feature list — it’s speed and consistency, applied to every single lead and customer rather than just the ones a rep has time for.

1. Speed to lead

Response time has one of the largest measurable effects on whether a lead ever becomes a customer. Research published in Harvard Business Review found that firms contacting a new lead within an hour were nearly seven times more likely to qualify it than firms that waited even one hour longer — and more than 60 times more likely than firms that waited 24 hours or more. An AI CRM removes the human bottleneck here entirely: it can acknowledge and begin qualifying a lead the moment it arrives, at any hour, without waiting on a rep’s schedule.

2. Personalization at scale

Small teams can’t hand-personalize every outreach message, but customers now expect it anyway. 73% of B2B buyers actively avoid vendors who send irrelevant outreach, which means generic, one-size-fits-all follow-up is actively costing deals, not just underperforming. An AI CRM pulls from a contact’s actual history to personalize outreach automatically, at a volume no individual rep could sustain manually.

3. Always-on follow-up

 A missed evening inquiry or weekend lead doesn’t have to sit untouched until Monday. AI CRM automation handles the first response and nurture sequence continuously, so engagement doesn’t depend on business hours.

4. Predictive signals

Instead of a rep noticing a customer has gone quiet after the fact, an AI CRM flags declining engagement early enough to act on it — a renewal conversation, a check-in call, or a targeted offer before the account is actually at risk.

Talk to ConvergeHub about setting this up for your pipeline — most of this runs automatically once lead scoring and follow-up sequences are configured.

How ConvergeHub’s AI CRM Delivers This

Each of these benefits maps to a specific part of the platform, not a generic “AI” label bolted onto old CRM software:

  • Automation Engine — dynamic, graphical workflows with adaptive triggers, which is what actually scores a lead and routes it the moment it comes in, rather than leaving it in a queue.
  • AI Summarizer — condenses emails, call transcripts, and meeting notes into a short summary and next-best-action, so a rep isn’t re-reading a contact’s entire history before following up.
  • Re-engagement Tools and Momentum Indicator — automated follow-up sequences paired with a metric that tracks engagement velocity, which is what flags a cooling account before it goes quiet for good.
  • Voice Assistant — a conversational interface for navigating the CRM and executing tasks hands-free, useful for a small team without a dedicated CRM administrator.
  • Low-Code/No-Code Builder — a drag-and-drop workflow designer and prebuilt campaign templates, which is what makes the automation above configurable without a developer.
  • Email Campaigns with built-in A/B testing — automated sequences with open/click tracking and performance analytics, extending the personalization-at-scale point into measurable campaign results.
  • Data Enrichment and Graph Builder — AI-driven enrichment of raw contact data, visualized through customizable graphs of leads, campaigns, and performance metrics.

Explore ConvergeHub’s full AI CRM feature set to see which of these would save the most time for your team first.

What to Look for When Choosing an AI CRM

Not every “AI-powered” CRM applies automation the same way. For a small business specifically, a few things matter more than a long feature list:

  • Automatic lead scoring and routing — not just tagging, but active prioritization based on engagement signals.
  • Generative follow-up that still sounds human — automation that drafts messages a customer would actually want to read, not templates.
  • No-code setup — a small team won’t have a dedicated CRM administrator, so configuration needs to be usable without one.
  • Transparent, predictable pricing — SMB budgets can’t absorb per-seat AI add-ons that scale unpredictably.
  • Data ownership and portability — the business’s customer data should never be locked into a platform it later wants to leave.

AI CRM Is Now the Standard, Not the Upgrade

The data is consistent across sources: AI CRM adoption is accelerating, response speed and personalization are now baseline customer expectations rather than differentiators, and the businesses capturing the strongest ROI are the ones actually using the automation built into their platform. For a small business competing against larger teams, an AI CRM is what makes fast, personalized, always-on engagement possible without adding headcount. Book a ConvergeHub demo to see how much of this can run on autopilot for your business.

Frequently Asked Questions

What is an AI CRM?

An AI CRM is a customer relationship management platform that uses artificial intelligence and automation to score leads, personalize outreach, predict customer behavior, and recommend next actions — going beyond the contact-storage function of a traditional CRM.

How is an AI CRM different from a regular CRM?

A traditional CRM is a system of record: it stores contacts, notes, and deal stages for a rep to review manually. An AI CRM is a system of action: it actively scores, prioritizes, drafts, and automates the next step based on that same data.

Can a small business realistically afford an AI CRM?

Yes. Most AI CRM platforms built for SMBs price per seat with AI features included rather than sold as expensive add-ons, and the automation itself reduces the need to hire additional sales or support staff to keep up with lead volume.

Does an AI CRM replace sales reps?

No. An AI CRM removes repetitive, time-consuming tasks — data entry, initial lead response, follow-up drafting — so reps spend more time on conversations that need a human, like negotiation and relationship-building.

How fast can an AI CRM respond to a new lead?

An AI CRM can acknowledge and begin qualifying a new lead within seconds of it arriving, any time of day, rather than waiting for a rep to see it during business hours.

What data does an AI CRM need to work well?

It needs clean, centralized contact and interaction history — emails, calls, website activity, and past deals. The more complete that record is, the more accurate its lead scoring and follow-up recommendations become.

Is customer data safe in an AI CRM?

Reputable AI CRM platforms apply the same security and compliance standards as traditional CRM software, including encryption and access controls, while using that data internally to power automation rather than sharing it externally.

How long does it take to see ROI from an AI CRM?

Most small businesses see measurable time savings within the first month, since automation immediately reduces manual lead entry and follow-up work. Revenue impact typically becomes visible over the following one to two sales cycles.

What features should a small business prioritize first in an AI CRM?

Automatic lead scoring and routing, AI-drafted follow-up, and no-code setup matter most early on — these deliver the fastest time savings without requiring a dedicated CRM administrator.

Does an AI CRM only help sales teams?

No. The same automation applies to customer support (faster case routing and response drafting) and marketing (personalized, behavior-triggered campaigns), making it useful across a small business, not just the sales pipeline.

How Much Time Can an MCA CRM Save Brokers Each Week?

Ask a broker where the week went and you will hear about calls, follow-ups, chasing bank statements, and rebuilding the same status report twice. The honest answer to the time question: a well-configured MCA CRM typically gives each rep back six to ten hours a week by automating follow-up, document chasing, reporting, and renewal tracking. Industry studies of sales automation commonly land in the same range, with reps reclaiming four to seven hours weekly from administrative work, and some teams recovering twelve or more.

That math matters because time is the only inventory a broker shop cannot buy more of. A five person shop that recovers even six hours per rep is holding a fresh thirty hour workweek, every week, without hiring anyone. This guide shows where those hours hide, how automation collects them, and how to measure the savings in your own shop instead of trusting anyone’s average.

How Much Time Can a Broker Shop Actually Save Each Week?

The direct answer is six to ten hours per rep in a typical shop, which means twenty to fifty hours a week for a small team. The exact number depends on three things: how manual the current process is, how many deals flow through the pipeline, and how much of the old routine survives the switch. Shops moving off spreadsheets and shared inboxes see the high end; shops already halfway automated see less.

The second half of the answer matters just as much. Saved hours only become revenue when they are reinvested in calls, and studies consistently find salespeople spend under a third of their week actually selling. The platform creates the capacity; the discipline of pointing it at merchants decides what it is worth.

Where the Hours Go in a Manual Shop

Before automating anything, it helps to see the leak. Track a broker’s week and the same tasks appear in every shop:

•  Building follow-up lists by hand and logging calls after the fact

•  Chasing bank statements, IDs, and voided checks through email threads

•  Re-entering the same merchant data into lender portals

•  Rebuilding pipeline status reports for the principal

•  Calculating commission splits across a pay cycle

•  Scanning the book for merchants nearing renewal eligibility

None of these tasks funds a deal by itself. Together they quietly consume the hours that would have gone into one more call, one more submission, one more renewal conversation.

Process Automation Efficiency: Task by Task

Process automation efficiency is not one big lever; it is six small ones. Each task below shows the typical weekly cost for a five rep shop running on manual process, and what automation does to it.

Task Manual Cost per Week With Automation Typical Recovery
Follow-up admin and call logging 8 to 12 hours Cadences and auto-logging 6 to 8 hours
Document chasing 5 to 8 hours Checklists and reminders 4 to 6 hours
Duplicate data entry 3 to 5 hours One record, push to funders 2 to 4 hours
Status reporting 3 to 4 hours Live dashboards 3 to 4 hours
Renewal list building 2 to 3 hours Eligibility alerts 2 to 3 hours
Commission preparation 2 to 4 hours Generated statements 1 to 3 hours

Add the right column and a five rep shop sits between eighteen and twenty-eight recovered hours a week. Those numbers are illustrative, but they are built from tasks every broker will recognize, and the audit in a later section lets you replace them with your own.

How an MCA CRM Delivers Manual Task Reduction

Manual task reduction is the mechanism behind every number in that table. A purpose-built MCA CRM does not speed up the old work; it deletes steps entirely, because the follow-up list builds itself, the reminder fires itself, and the report renders itself. Deleting a step beats accelerating it every time.

The savings compound in a second way: speed. Automated first touches go out in minutes instead of hours, and faster contact reliably lifts contact rates on fresh inquiries. The same recovered hour spent earlier in the deal cycle is worth more than an hour spent later, because merchants apply to several funders at once and the first credible voice frames the deal.

What the Saved Hours Are Worth

Capacity math turns hours into decisions. Commonly cited figures put the revenue lift from CRM automation in the range of one quarter to nearly half, and the time freed is the input behind it. A rep who reinvests six reclaimed hours into dials and renewal calls is simply working a longer selling week at zero added cost.

Platforms such as ConvergeHub are built around exactly this trade, bundling follow-up automation, document workflows, and reporting into the same per-user subscription. Providers in this space commonly report close-rate improvements of up to forty percent after automation is fully adopted. Treat vendor claims as directional, but the underlying mechanism is real hours pointed at revenue.

Shop Size Weekly Hours Recovered What Teams Do With It
Solo broker 6 to 10 More dials, same days
Two to three reps 12 to 25 Faster first touch, cleaner book
Five reps 18 to 40 Dedicated renewal coverage
ISO with partners 25 to 50 Submissions without re-keying

For perspective on the bigger end: automation research suggests a ten rep team can recover forty to fifty hours a week, the equivalent of adding two full-time sellers without adding headcount. Even at half that figure, the subscription pays for itself in reclaimed capacity.

How to Measure It in Your Own Shop

Averages are marketing; your own audit is evidence. Run it for one week before the switch, and repeat it after the first full cycle of deals has flowed through the new system.

•  Time spent building follow-up lists and logging calls

•  Time spent requesting and chasing documents

•  Time spent re-entering data into lender portals

•  Time spent building status reports

•  Time spent on commission math

•  Time spent hunting for renewal-eligible merchants

Compare the two weeks task by task, then multiply the difference by your headcount and your loaded hourly cost. That single calculation, hours saved times cost per hour, is the number to hold against the subscription price. Most shops find the software costs a fraction of what the manual routine was quietly billing them.

Savings arrive in waves rather than all at once. Follow-up automation pays in the first week, document chasing in the first few deals, reporting the first time the principal skips the Monday rebuild, and renewals the first time an alert surfaces a merchant nobody had flagged.

Making the Switch Without Losing a Week to Setup

The irony of saving time is that switching systems costs some, and shops delay upgrades for fear of the dip. In practice the mechanics are small: export the book, map the fields, import the history, and run the old sheet as a frozen reference for a couple of weeks.

If you want the savings without the setup homework, Contact us and we will handle the import, configure the cadences, and train the team in one short project. The goal is a transition measured in days, so the recovered hours start accruing while this week’s pipeline keeps moving.

Frequently Asked Questions

How many hours does a CRM save a broker each week?

Commonly cited automation studies put it at four to seven hours per rep, and cash advance shops with heavy document and submission flows often land higher. A realistic planning range is six to ten hours per rep. Your own one week audit gives the real number.

Which tasks benefit most from automation?

Follow-up administration, document collection, and status reporting, in that order. Together they are usually half of the recoverable time. Renewal tracking and commission preparation add the rest once the book matures.

Does manual task reduction help small teams too?

Yes, and often more visibly, because a two person shop has no slack hours to absorb admin. When one partner stops chasing statements and building reports, the recovered time goes straight into calls. Small teams feel the same hours more.

How do I measure the savings in my shop?

Log task times for one week before switching and again after the first full deal cycle, then compare task by task. Multiply the difference by headcount and hourly cost. That figure, held against the subscription, is the entire business case.

Does ConvergeHub automate broker workflows?

Yes. Follow-up cadences, document checklists, pipeline dashboards, and renewal alerts are configured around the deal cycle rather than bolted on. Setup is scaled to the shop, so a small team goes live without a project plan.

Conclusion

An MCA CRM saves a typical broker rep six to ten hours a week and a small shop somewhere between a shift and a full workweek, by automating follow-up, document chasing, reporting, and renewal tracking. The hours are real, measurable, and reinvestable, and the shops that win with automation are the ones that point the reclaimed time straight at merchants instead of at longer coffee breaks. Averages are a starting point; a one week audit makes the number yours.

To see what your shop’s hours add up to, schedule an appointment with ConvergeHub. We will map your current routine, estimate the recovery task by task, and configure the automation that returns those hours to selling. Time is the one inventory you cannot restock, so spend it where it funds deals.

What Should a Small MCA Broker Shop Look for in a CRM?

A two-person brokerage does not need a shrunken copy of enterprise software; it needs a short list of things done perfectly. The right MCA CRM for a small shop does five jobs well: captures every inquiry, keeps one shared pipeline, automates follow-up, tracks documents and lender submissions, and reminds the team when renewals come due. Everything beyond that is either headroom for growth or a monthly bill for features a boutique shop will never open.

That framing matters because small shops buy software twice, once for the team they have and once for the team they imagine. Boutique broker software should match the reality: per-user pricing, minimal training, and workflows that a principal can run without a consultant on retainer. This guide lists the features that actually move deals for small teams, the ones to skip, and the questions that expose the right fit in a demo.

What Should a Small Shop Expect From an MCA CRM?

The short answer is coverage of the full deal cycle without complexity. A platform built for cash advance work should deliver the essentials on day one:

•  Lead capture from forms, referrals, and ISO partners with source tracking

•  One shared pipeline with stages from new inquiry to funded and renewal

•  Automated first touches and follow-up cadences with consent logging

•  Document checklists that chase bank statements and IDs on their own

•  Submission tracking across multiple funders with offer status in one place

•  Renewal reminders and commission records attached to every deal

Notice what is absent: seat minimums, implementation consultants, and month-long onboarding. A small shop should expect to be productive within a week, not a quarter. Pay for the shop you run today, with a little room for the shop you are becoming.

Small Team CRM Features That Actually Move Deals

Small team CRM features earn their keep by replacing memory and busywork. When every person wears three hats, the system has to carry the routine so people can carry the conversations. Four capabilities do most of the heavy lifting.

One Shared Pipeline Everyone Can Read

In a small shop, the pipeline is the business. A visual board with stages like New, Contacted, Qualified, Documents, Submitted, Offer, Funded, and Renewal lets a principal see the whole shop in one glance. Nothing lives in a personal notebook, and a deal never stalls invisibly.

Follow-Up That Runs Itself

Speed decides deals, and small teams are busy by definition. Automated email and text sequences, call tasks, and dialer queues keep every inquiry moving until a human takes over. Consent and opt-out logging keeps the outreach compliant without adding a compliance officer.

Documents and Submissions in One Place

Chasing bank statements eats hours that a small shop cannot spare. Checklist automation requests, reminds, and tracks each document, while submission records show which funder has the file, what offer came back, and what is still outstanding. One screen replaces five browser tabs and a shared drive.

Renewals and Commissions on Autopilot

Renewals are the margin engine for a small book, and commission records are the reason partners stay. The platform should flag merchants approaching renewal eligibility and store splits and buy rates against each deal. That turns quiet weeks into scheduled, warm conversations.

Boutique Broker Software: What Not to Overpay For

The small-shop version of overbuying looks innocent. Enterprise tiers advertise single sign-on, granular role hierarchies, custom objects, and API platforms that a five person team will configure once and never touch. Seat minimums quietly double the bill, and professional-services packages outprice the licenses themselves.

The counterpoint is equally real: buying too small costs deals. A free contact manager with no pipeline, no cadences, and no renewal tracking quietly leaks the follow-ups and reflows that keep a boutique shop alive. The goal is the narrow band in the middle: industry-shaped features, per-user pricing, and setup that fits between funding deals.

The Buying Checklist: Questions That Expose the Right Fit

A checklist keeps the decision honest when demos get charming. The right MCA CRM for a small shop answers every question below without a work-around, because each workaround becomes a spreadsheet within a quarter. Bring this list to every demo and watch what happens.

Question to Ask Why It Matters Green Flag in the Demo
Can we live in a week? Small shops cannot fund a quarter-long project Setup shown, not promised
Are deal fields native or custom? Factor rates and renewals should exist already Fields visible without a builder
How are follow-ups triggered? Speed to lead decides contact rates Cadences fire from the inquiry itself
How do submissions track across funders? Multi-funder shops live on offer status One screen per deal
What does renewal support look like? Reflows are the margin engine Eligibility alerts, not manual dates
What is the true monthly cost? Seat minimums hide the real bill Simple per-user math

Score every platform the same way, and weigh the failures honestly. A vendor that stumbles on the basics in a demo will stumble worse in week three.

Pricing and Setup: What a Small Shop Should Budget

The budget for a small shop is simple math: per-user price times heads, plus setup. A three person brokerage should be able to calculate its annual software cost in one line, and that cost should be visible in the deal margin, not hidden in an invoice surprise. Ask about training, data import, and what support is included before signing.

Platforms such as ConvergeHub are priced exactly this way, per user with sales, marketing, service, and billing modules bundled rather than sold separately. For a boutique shop, bundling removes the add-on creep that turns a modest subscription into a stack. Setup scales to the team instead of assuming an implementation department.

Buy Now Reason Can Wait Until
Shared pipeline and cadences Core deal flow from day one Already needed
Document checklists Saves hours weekly Already needed
Submission tracking Multi-funder visibility As soon as you submit to two funders
Renewal forecasting Protects the margin engine First renewals appear
Syndication and investor reporting Only relevant at scale You fund your own deals

Switching From Spreadsheets or a Free Tool

The move is smaller than it feels. Merchant lists, statuses, notes, and renewal dates export from any sheet, and mapping them into structured deal fields usually takes one working session. Most small shops run the old sheet as a frozen reference for a few weeks, then stop opening it entirely.

If you would rather keep funding deals than map columns, Contact us and we will handle the import, deduplicate the merchants, and train the team in one short project. A two person shop should be live while this week’s pipeline keeps moving.

Where Small Shops Go Wrong in the First Year

The first mistake is treating go-live as the finish line. A platform adopted but not configured quietly reverts to old habits within weeks, and the team ends up running the software beside the spreadsheet instead of inside it. Plan the first month like a project: import the book, build the cadences, and review the pipeline together every morning until the habit sticks.

The second mistake is skipping training because the team is small. Two reps who each use the system differently produce data nobody can report on, and the owner loses the visibility that justified the purchase. An hour of shared training costs less than one mis-entered renewal date.

The third is chasing features instead of adoption. Every unused module on the shelf was bought for a future that arrived late, and every rep who stopped logging calls turned the report into fiction. Small shops win when the basics are used religiously, so choose the software your team will actually touch every single day.

Frequently Asked Questions

What is the best type of CRM for a small cash advance broker shop?

One built for the deal cycle rather than general sales. Look for native fields for factor rates, pipeline stages that match submissions and funding, document checklists, and renewal tracking. Simplicity matters more than feature count.

How many users justify paying for a platform?

Even one. A solo broker who misses follow-ups or renewal dates loses more per month than a per-user subscription costs. The question is not headcount; it is whether the deal cycle runs on memory.

Which small team CRM features matter most?

A shared pipeline, automated follow-up cadences, document checklists, submission tracking, and renewal reminders, in roughly that order. Reporting is valuable once data exists, but it cannot rescue deals the basics never captured.

Is a free CRM good enough to start?

Free contact managers store names and notes, and that is where they stop. The features that actually fund deals, cadences, checklists, submissions, renewals, sit behind paid tiers for a reason. Free is fine for week one and expensive by the first renewal.

Does ConvergeHub fit small broker shops?

Yes. Per-user pricing, bundled modules, and setup scaled to the team make it practical for a two person shop and roomy enough for growth into ISO partnerships. Configuration follows the shop’s stage rather than an enterprise template.

Conclusion

A small shop’s MCA CRM should capture inquiries, run the follow-up, track the documents and submissions, and protect the renewals, all at a per-user price that fits the margin. Skip the enterprise tier, skip the consultants, and insist on a demo that answers a checklist instead of a pitch deck. The right system for a boutique shop is the one the team actually uses every day.

To see how that list scores against your shop, schedule an appointment with ConvergeHub. We will map your current workflow, configure the pipeline your team has been improvising, and have you working deals while the paperwork catches up. Small shops win on speed; the software should keep up.

Cloud-Based vs On-Premise MCA CRM: Which Should Funders Choose?

The hosting question sounds like an IT decision, but for a funding company it is really a speed, security, and money decision. For most funders today, a cloud-based MCA CRM is the better choice, because it puts the entire deal pipeline behind a login instead of behind a server closet: reps work from anywhere, updates and security patches arrive automatically, and the cost becomes a predictable per-user subscription instead of hardware, licenses, and an IT salary. On-premises still makes sense for a specific kind of shop, the one with existing infrastructure staff, hard data-control mandates, or deep custom integrations. This comparison lays out both paths honestly so you can choose based on your team, not on vendor marketing.

The decision also shapes how your business runs day to day. Underwriters, closers, servicing staff, and renewal teams all touch the same deals, and where the software lives determines how easily they can reach it. Here is what each deployment model actually means, where each one wins, and how to run the numbers that settle it.

What Should Funders Know Before Choosing an MCA CRM Deployment?

The short answer is that deployment is about who runs the servers and who answers when something breaks. A cloud system is vendor-hosted software: the provider runs the infrastructure, handles backups and patches, and your team logs in through a browser. On-premise means the software runs on servers you own, inside your office or a data center you lease, maintained by your staff or a contracted partner.

There is also a middle path worth knowing. A hosted CRM deployment, sometimes called private cloud or single-tenant hosting, places a dedicated instance of the software with a provider instead of mixing it into a shared environment. It trades some of the shared platform’s cost efficiency for stronger isolation. For most funders, though, the practical choice comes down to standard cloud versus owned servers.

Each model carries assumptions about your team. Cloud assumes the vendor is better at infrastructure than you are, which is usually true. On-premise assumes you have, or will hire, the people to patch, back up, monitor, and recover a business-critical system at any hour.

Where Cloud Deployment Wins for Funding Teams

The cloud case rests on three pillars that map directly to how funding shops operate. None of them is about hype; they are about hours and headcount.

Access From Anywhere

Deals do not respect office walls. Reps call merchants from home, closers check files after hours, and principals review pipelines while traveling, all of which a browser handles natively. An on-premise setup typically requires a VPN or remote desktop layer that adds friction precisely when speed matters. Fast follow-up wins merchants, and accessibility is the quiet foundation of fast follow-up.

Updates and Security Without a Project

Cloud platforms ship improvements continuously, so factor rate fields, renewal alerts, and compliance features arrive without an implementation cycle. Security patches land the same way, which matters because funding data, bank statements, IDs, and processing details, is exactly what attackers want. Vendors also invest in certifications, encryption in transit and at rest, audit trails, and regional data centers at a level most individual companies cannot replicate alone.

Paying for Software, Not Server Closets

Cloud pricing is an operating expense: a per-user subscription that scales with the team. On-premise is capital expense: servers, licenses, an implementation project, and one or more full-time IT roles to keep it alive. For small and mid-size funders, that difference often decides the question by itself.

The Case for On-Premise (When It Still Makes Sense)

Some funders have legitimate reasons to keep software in-house. Strict data-control or data-residency mandates, a legacy system the platform must integrate with at the database level, or an existing IT department with idle capacity can all justify it. Air-gapped environments for highly sensitive operations are a real, if rare, requirement.

The honest trade-offs follow from that control. Upgrades become projects that often require new licenses and reimplementation, which is why on-premise shops frequently run older versions for years. Backups, disaster recovery, and monitoring become your responsibility every hour. And access outside the office depends on whatever remote layer you build and maintain.

On-premise is not wrong; it is a commitment. It makes sense when the shop already owns the muscle to run it and a requirement that cloud cannot meet.

Data Accessibility for Lenders: The Real Deciding Factor

Data accessibility for lenders is where this decision stops being theoretical. A cloud-native MCA CRM puts the complete deal history, documents, remittance data, and renewal timeline in front of every authorized user the moment they need it, on any device. Underwriting sees the same record the closer it sees, and servicing never waits for a file transfer.

Access controls matter as much as access. Modern platforms enforce role-based permissions so a rep sees their pipeline while management sees the whole book, with multi-factor authentication and audit logs recording every view and change. Merchant information stays protected without becoming hard to reach.

On-premise accessibility usually means VPN logins, version conflicts on shared files, and after-hours gaps that translate into missed calls. When a renewal-eligible merchant calls at eight in the evening, the team with browser access answers with full context. The team without it calls back the next business day, often after a competitor has already framed the deal.

Side-by-Side: Cloud vs On-Premise at a Glance

Here is how the two models compare across the factors funders weigh most:

Aspect Cloud (SaaS) On-Premise
Upfront cost Low, per-user subscription Servers, licenses, implementation
Ongoing cost Predictable operating expense IT staff, maintenance, power
Access Any browser, any device Office network or VPN
Updates Continuous and automatic Upgrade projects, often delayed
Security posture Vendor certifications, monitoring Your tools, your team, your hours
Scaling Add users instantly Buy and configure capacity
Business continuity Built-in redundancy and backups Your disaster recovery plan
Data control Contractual, with exports Total, on your hardware

Read the table as a mirror, not a scoreboard. Cloud trades some infrastructure control for capability you would otherwise have to build. On-premise trades convenience and cost for ownership.

Total Cost of Ownership: The Number That Decides

Sticker price hides more than it reveals here. A fair comparison looks three years out and counts everything: licenses, hardware, salaries, downtime, and the cost of staying current.

Cost Line Cloud On-Premise
Initial investment Minimal Servers plus implementation
Recurring fees Per-user subscription Maintenance contracts, hosting
Staffing None required One or more full-time roles
Upgrades Included New licenses and projects
Backup and recovery Included Separate infrastructure
Adding users Instant, prorated Capacity planning and setup

The pattern is consistent: on-premise costs are lumpy, delayed, and easy to underestimate, while cloud costs are visible and predictable. Finance teams tend to prefer the second kind. Cloud platforms such as ConvergeHub bundle hosting, updates, backups, and support into the per-user price, which is why the subscription looks larger than it is.

Migration and Hybrid Paths

Moving from on-premise to the cloud is a routine project, not a leap of faith. Merchant records, deal history, documents, and configurations export from most systems, and the real work is mapping fields and validating data before the cutover. Many shops run a hybrid period, keeping the old system frozen as a reference while the team works in the new one.

If the migration map looks daunting, Contact us and we will assess your current deployment, plan the export, and run the transition with your team side by side. The goal is continuity: every deal, document, and renewal date lands where your staff expects to find it.

Ask any vendor the exit questions up front, cloud or otherwise. Can you export your data at any time, in a usable format? Who owns the data contractually? How are deletions handled if you leave? A confident provider answers all three without hesitation, and those answers are the real measure of data ownership.

How to Decide: Questions for Your Team

A short conversation settles this faster than a vendor demo. Ask:

•  Do reps, closers, or principals work outside the office regularly?

•  Who patches, backs up, and restores the system at odd hours today?

•  What would three years of total cost look like under each model?

•  Does any mandate require data to stay on hardware you control?

•  How quickly do you need to add users, offices, or partners?

If the honest answers lean toward remote work, lean staffing, and fast growth, the cloud decision makes itself. If you have an IT bench and a control mandate, on-premise earns its keep.

Frequently Asked Questions

Is a cloud CRM secure enough for merchant bank statements and IDs?

Yes, in most cases more secure than an office server. Reputable vendors run encryption in transit and at rest, multi-factor authentication, role-based access, and audit trails, backed by security certifications most individual companies never attain. Most real breaches start with compromised credentials, not infrastructure.

What does hosted CRM deployment actually mean?

It means the vendor runs the software on infrastructure you do not maintain, and your team accesses it through a browser under a subscription. A private hosted variant gives you a dedicated instance for stronger isolation. Either way, patching, backups, and uptime are the provider’s job.

Is on-premise ever cheaper in the long run?

Occasionally, for large shops that already employ IT staff and own infrastructure. For most small and mid-size funders, total cost of ownership favors the cloud once salaries, upgrades, and recovery planning are counted honestly.

Can we move from on-premise to the cloud without losing history?

Yes. Records, documents, and configurations export from most legacy systems, and the migration centers on field mapping and validation. A frozen reference copy of the old system usually covers the transition period.

Does ConvergeHub offer cloud deployment?

Yes, it is cloud-native. Hosting, updates, backups, and support are bundled into the per-user subscription, and data stays exportable. Setup is configured around the funder’s workflows rather than the other way around.

Conclusion

A cloud-based MCA CRM wins for most funders because it converts infrastructure problems into product features: anywhere access, automatic security, predictable cost, and instant scaling. On-premise remains a rational choice for shops with real IT capacity and a genuine control mandate. The wrong answer is the one that assumes your current team will happily become a sysadmin department.

To pressure-test the choice against your actual shop, schedule an appointment with ConvergeHub. We will review your team, your access needs, and your costs, then map the deployment that fits how you fund. The best hosting decision is the one your staff never has to think about again.